Talk to an originator(215) 555-0145Start pre-qualification

NMLS #XXXXXXX · Equal Housing Opportunity

Loan programs

See all 16 programs
(215) 555-0145

NMLS #XXXXXXX · Equal Housing Opportunity · PA, NJ, DE, MD

Start pre-qualification

Tools and rates

See every tool
(215) 555-0145

NMLS #XXXXXXX · Equal Housing Opportunity · PA, NJ, DE, MD

Start pre-qualification

Philadelphia · since 2009

Lending with the underwriter down the hall

Purchase, refinance and investor mortgages across Pennsylvania, New Jersey, Delaware and Maryland. Flat fee, real arithmetic, and an answer you can act on today.

  • In-house underwriting
  • Flat $1,095 origination
  • No application fee
The Philadelphia skyline at dusk from across the Schuylkill
  • 1,284Closed-file client surveys since 2009
  • 12 daysMedian complete file to clear-to-close
  • 4 statesPA, NJ, DE and MD
  • $1,095Flat origination fee, any loan size

Four ways into the same balance sheet

Every program has its own page with the guideline table, the process, the cost and a plain list of what tends to go wrong.

  • Brick row homes on a Philadelphia street

    Buying in Philadelphia

    Six purchase programs from 3% down conventional to zero-down VA and USDA, with the score floors and down payment minimums published rather than hinted at.

    See purchase programs
  • 16

    loan programs, each with its own page, its own guideline table and its own honest list of what to watch out for.

    All programs
  • Refinance documents being signed

    Refinancing

    We publish the break-even month before you sign a disclosure. Sometimes it says do not do this.

    Refinance options
  • Renovated living space in a city home

    Tapping equity

    A HELOC or a fixed second leaves a low first-mortgage rate exactly where it is. Frequently the cheaper answer.

    Equity options
  • Brick multifamily rental building

    Investor lending

    DSCR, bridge, fix and flip and blanket portfolio loans. Qualified on the property, not your returns.

    Investor desk

Watch the interest give way to principal

A real amortization schedule for a real loan. Change any figure and the payment, the split and all thirty years of the table recompute.

Term

Philadelphia County bills property tax at 1.398% of assessed value. Sample rate, sample assessment.

Monthly principal, interest, tax and insurance$2,544Escrowed. Add association dues and mortgage insurance separately if they apply.
Loan amount
$320,000
Principal and interest
$1,944
Property tax, monthly
$466
Insurance, monthly
$134
Total interest over the term
$379,967
Final payment
October 2056
Each bar is one year of payments, split between interest and principal. In year one, 16% of what you pay reduces the balance.
Year 1Year 15Year 30
Principal Interest

The schedule, year by year

Annual amortization schedule
YearInterest paidPrincipal paidBalance at year endEquity from principal
1$19,493$3,839$316,161$3,839
2$19,252$4,081$312,081$7,919
3$18,995$4,338$307,743$12,257
4$18,721$4,611$303,132$16,868
5$18,431$4,902$298,230$21,770
6$18,122$5,210$293,020$26,980
7$17,794$5,539$287,481$32,519
8$17,445$5,887$281,594$38,406
9$17,074$6,258$275,336$44,664
10$16,680$6,653$268,683$51,317
11$16,260$7,072$261,611$58,389
12$15,815$7,517$254,094$65,906
13$15,341$7,991$246,103$73,897
14$14,838$8,494$237,609$82,391
15$14,303$9,029$228,579$91,421
16$13,734$9,598$218,981$101,019
17$13,129$10,203$208,778$111,222
18$12,487$10,846$197,933$122,067
19$11,803$11,529$186,404$133,596
20$11,077$12,255$174,148$145,852
21$10,305$13,027$161,121$158,879
22$9,484$13,848$147,273$172,727
23$8,612$14,720$132,553$187,447
24$7,684$15,648$116,905$203,095
25$6,699$16,634$100,271$219,729
26$5,651$17,682$82,590$237,410
27$4,537$18,795$63,794$256,206
28$3,353$19,980$43,814$276,186
29$2,094$21,238$22,576$297,424
30$756$22,576$0$320,000

Scroll the table sideways and down to read the whole schedule.

Sample figures. Rates, tax rates and insurance costs shown are illustrations for this demonstration site, not a quote and not an offer to lend. Your actual payment depends on credit, program, property and the escrow analysis at closing.

Which door you can actually walk through

Six programs, six credit boxes. Read down the column that stops you: the score floor, the down payment, the ratio cap or the mortgage insurance you cannot cancel.

Loan program eligibility matrix
ProgramMinimum scoreMinimum downMaximum DTIMortgage insuranceLimit, one unitOccupancy
Conventional conforming620 (640 under 5% down)3% first-time, 5% repeat45%, to 50% with reservesCancellable at 80% LTV$832,750Primary, second, investment
FHA 203(b)580 (500 with 10% down)3.5%43% manual, 50%+ with TOTAL1.75% upfront, 0.55% annual, life of loan above 90% LTV$524,225Primary only
VANo VA minimum, 600 overlay0%41% plus residual income testNone. Funding fee 2.15% first useNone at full entitlementPrimary only
USDA guaranteed640 for GUS0%29/41, higher with GUS Accept1.00% upfront, 0.35% annualIncome capped at 115% AMIPrimary only
Jumbo portfolio700 (680 with 30% down)10% to $1m, 20% to $2m43%, to 45% with 12 months reservesNone$832,751 to $3,000,000Primary, second
DSCR investor660 (700 for best tier)20% purchase, 25% cash-outNot used. DSCR 1.10 or higherNone$100,000 to $2,000,000Investment only

Swipe the table sideways to compare every column.

Sample guideline figures for 2026. Loan limits, score floors and ratio caps are illustrations for this demonstration site. Agency limits change annually, automated underwriting overrides published ratio caps in both directions, and Keystone applies its own overlays where stated.

Read all sixteen programs

Two ratios decide what you can borrow

Front-end is housing over income. Back-end is all debt over income. Every program caps them differently, and the lower of the two is what actually binds.

Program

Monthly debts means minimum card payments, car and student loans, personal loans and court-ordered support. Not groceries, utilities or childcare.

Maximum purchase price at these ratios$491,000Loan of $442,014 with $2,686 principal and interest
Housing ratio (front-end)38.2%

Cap for this program: no separate cap

Total debt ratio (back-end)45.0%

Cap for this program: 45%

Maximum total housing payment
$3,625
Binding constraint
The back-end ratio
At the conservative 28/36 rule
$2,660
Program
Conventional conforming

Ratios are maximums, not targets. An approval at 45% is still an approval that leaves you 45% committed before groceries. Sample figures for a demonstration site; automated underwriting, reserves and residual income change the real answer.

How Keystone works

A Keystone underwriter and originator reviewing a file together

In house since 2009

The underwriter is on the fourteenth floor

Most lenders your size send files to a processing center in another state and then relay the answers back to you a day late. Ours sit two doors from the originators. When a condition looks wrong, someone walks over and asks.

That is why our conditions arrive in one batch instead of a weekly trickle, and why our median from complete file to clear-to-close on conventional purchases is 12 business days.

  • Named underwriter on every pre-approval letter
  • Conditions issued once, not weekly
  • Appraisals reviewed in house before underwriting
How we work
Rental properties in a Philadelphia neighborhood

Investor desk

Qualified on the property, not your tax returns

Landlords who depreciate aggressively keep their tax bill low and their qualifying income lower. A conventional underwriter reads the bottom line. A DSCR underwriter reads the rent roll.

Amara runs this desk and owns eleven doors of her own, which is why her models carry realistic vacancy and turn costs rather than the appraiser's best case.

  • No personal debt-to-income calculation
  • No cap on financed properties
  • LLC closings at no additional charge
Open the investor desk

Every line on a Philadelphia closing

Four buckets, one total. Only the first is ours, and it is the smallest. The largest is a transfer tax the city sets and the contract splits.

  • $400,000 purchase
  • $320,000 loan
  • 20% down
  • Philadelphia County, PA
  • $12,463 total

Lender fees

What Keystone charges to originate, underwrite and close the loan. This is the only section we control, and it is flat.

$1,253
Origination and underwriting Flat, not a percentage of the loan
$1,095
Credit report, joint
$68
Flood zone certification
$12
Tax service fee
$78
Discount points Optional. See the buydown grid
$0

Negotiable? Fixed. We publish it because a percentage-based origination fee on a $320,000 loan would be roughly three times this.
Third-party services

Ordered by us, performed by others, paid to them. Pennsylvania title insurance rates are filed with the state, so they do not vary by provider.

$4,350
Appraisal, single family
$625
Lender's title insurance policy PA filed rate on $320,000
$2,205
Owner's title policy, simultaneous issue
$150
Title search and examination
$325
Settlement and closing fee
$595
Survey, where required
$450

Negotiable? Partly. You may shop the settlement agent and survey. Title insurance rates in Pennsylvania are filed and identical everywhere.

Recording and transfer tax

Philadelphia has one of the highest combined transfer taxes in the country: 3.278% to the city plus 1.00% to the Commonwealth. Custom splits it evenly between buyer and seller.

$8,868
Recording, deed and mortgage
$312
PA realty transfer tax, buyer half 1.00% total, split by custom
$2,000
Philadelphia transfer tax, buyer half 3.278% total, split by custom
$6,556

Negotiable? Not by us, but the split is contractual. In a soft market buyers frequently negotiate a larger seller share.

Prepaid interest and escrow

Not a cost of borrowing. This is your own money moving forward in time: interest to month end, the first insurance year, and the escrow cushion.

$3,308
Prepaid interest, 12 days at $54.44 Closing on the 19th
$653
Homeowners insurance, 12 months
$1,340
Escrow: 3 months property tax
$1,092
Escrow: 2 months insurance
$223

Negotiable? Timing only. Closing on the 28th instead of the 19th cuts prepaid interest by about $490.

Cash to close, excluding the down payment

$12,463

On a $400,000 purchase with 20% down, settling on the 19th of the month. Sample figures for a demonstration site. Your Loan Estimate itemizes the real numbers within three business days of application.

Read the full cost sheet

A lock is a contract, with an expiry and a worst case

Longer locks cost more because the lender is hedging longer. Here is what each period costs, who pays for an extension, and the one float-down you get for free.

Rate sheets and lock pricing on a screenA borrower checking lock dates at a home deskA lock agreement being signed at a closing tableLoan officers reviewing a lock calendar in the office

0.125 points per seven days, to a maximum of 30 days. If the delay is ours, we pay for the extension. That is written into our lock policy rather than decided case by case.

If the market improves by 0.250% or more after you lock, you may float down once to the new market rate less 0.125%. It must be requested at least ten calendar days before settlement, and it resets nothing else about your file.

An expired lock is repriced at worst-case pricing: the higher of the original locked rate or current market. This is industry standard and it is why we monitor lock calendars daily rather than weekly.

You can lock at application, before the appraisal is back. If the value comes in low and the loan-to-value changes tier, the pricing adjustment changes with it. We tell you the exposure in advance.

Lock period pricing
Lock periodCostWhen we use it
30 daysBase pricingRefinances and quick settlements where the file is already complete
45 days0.125 pointsOur default on purchases. Most Philadelphia contracts settle inside it
60 days0.250 pointsFiles with a subject-to-sale contingency or a slow condominium questionnaire
90 days0.500 pointsNew construction and extended settlement dates

Sample lock pricing. Extension and float-down terms shown are an illustration of a written lock policy, not a commitment. Lock pricing moves with the secondary market.

The Benjamin Franklin Bridge and the Philadelphia waterfront

Market insights

What the Philadelphia numbers are doing this quarter

County-level median price, days on market, assessment changes and the transfer tax arithmetic, refreshed every quarter and written for people making a decision rather than reading a press release.

  • Median price and days on market for all six of our markets
  • What the abatement phase-down does to your escrow in year four
  • Where rental yields still support a 1.20 coverage ratio
Read this quarter

Six people, one office, one floor

You will speak to the person whose name is on your pre-approval letter. NMLS identifiers below are placeholders pending the client's licensing details.

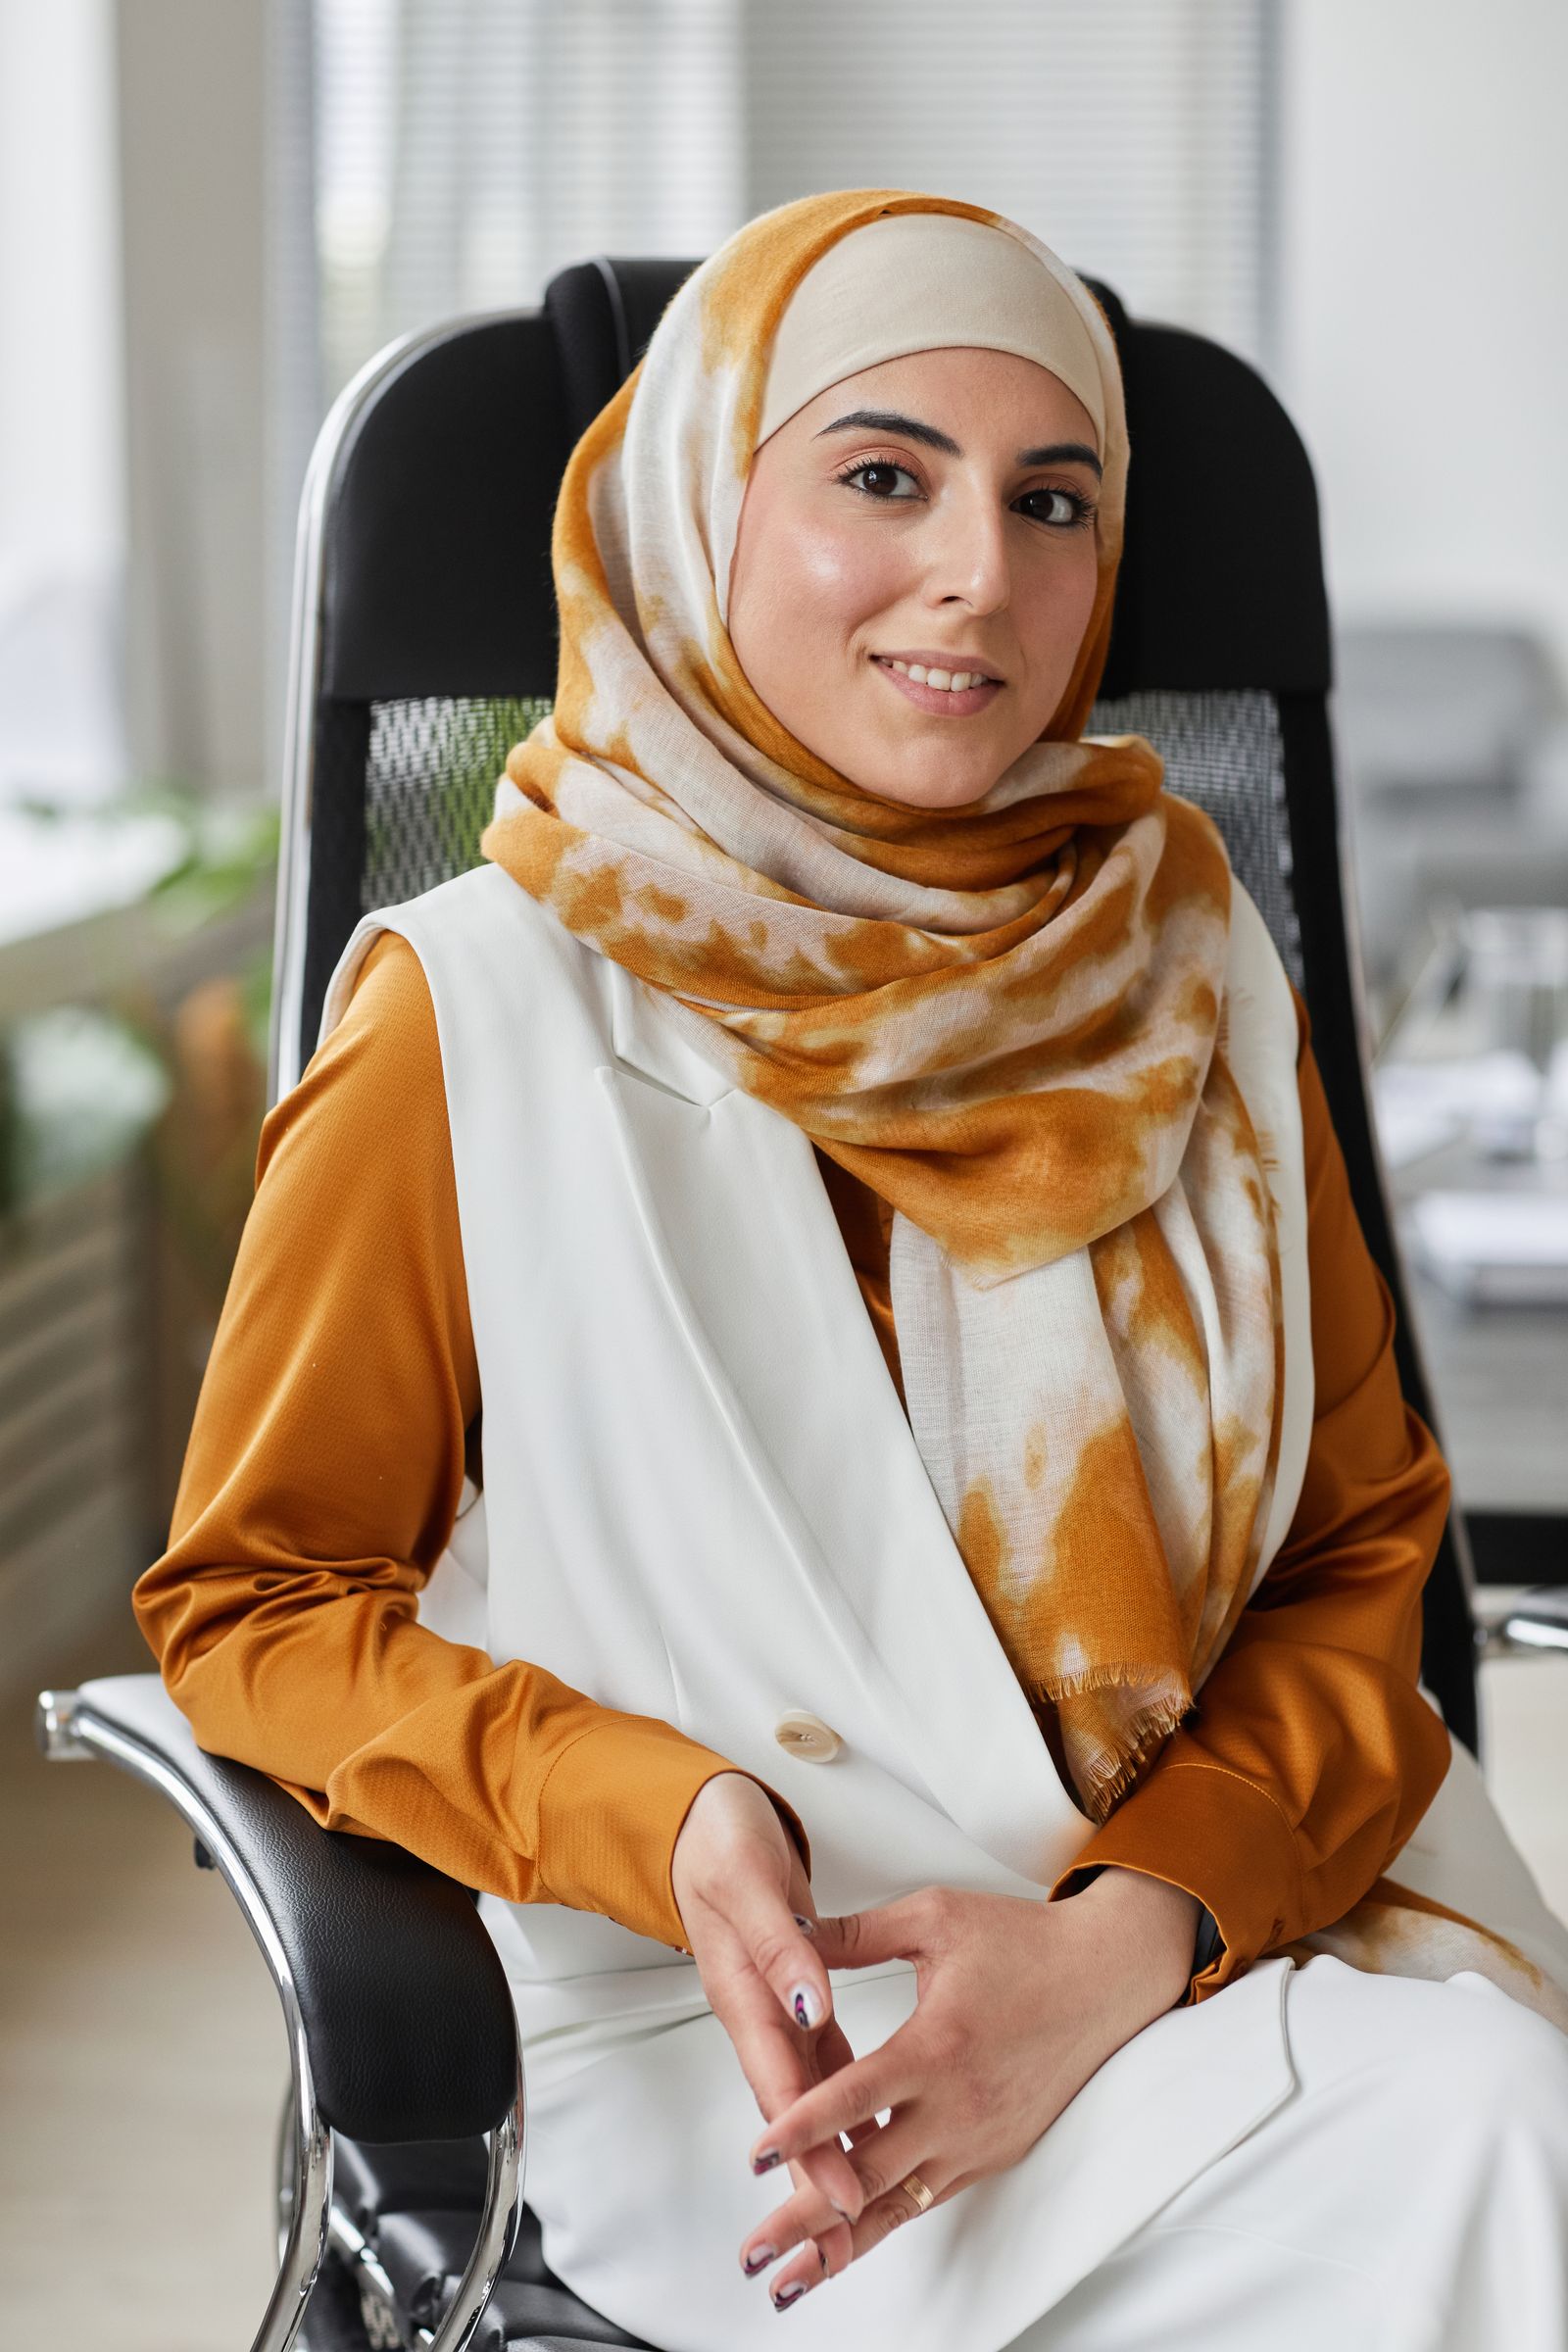
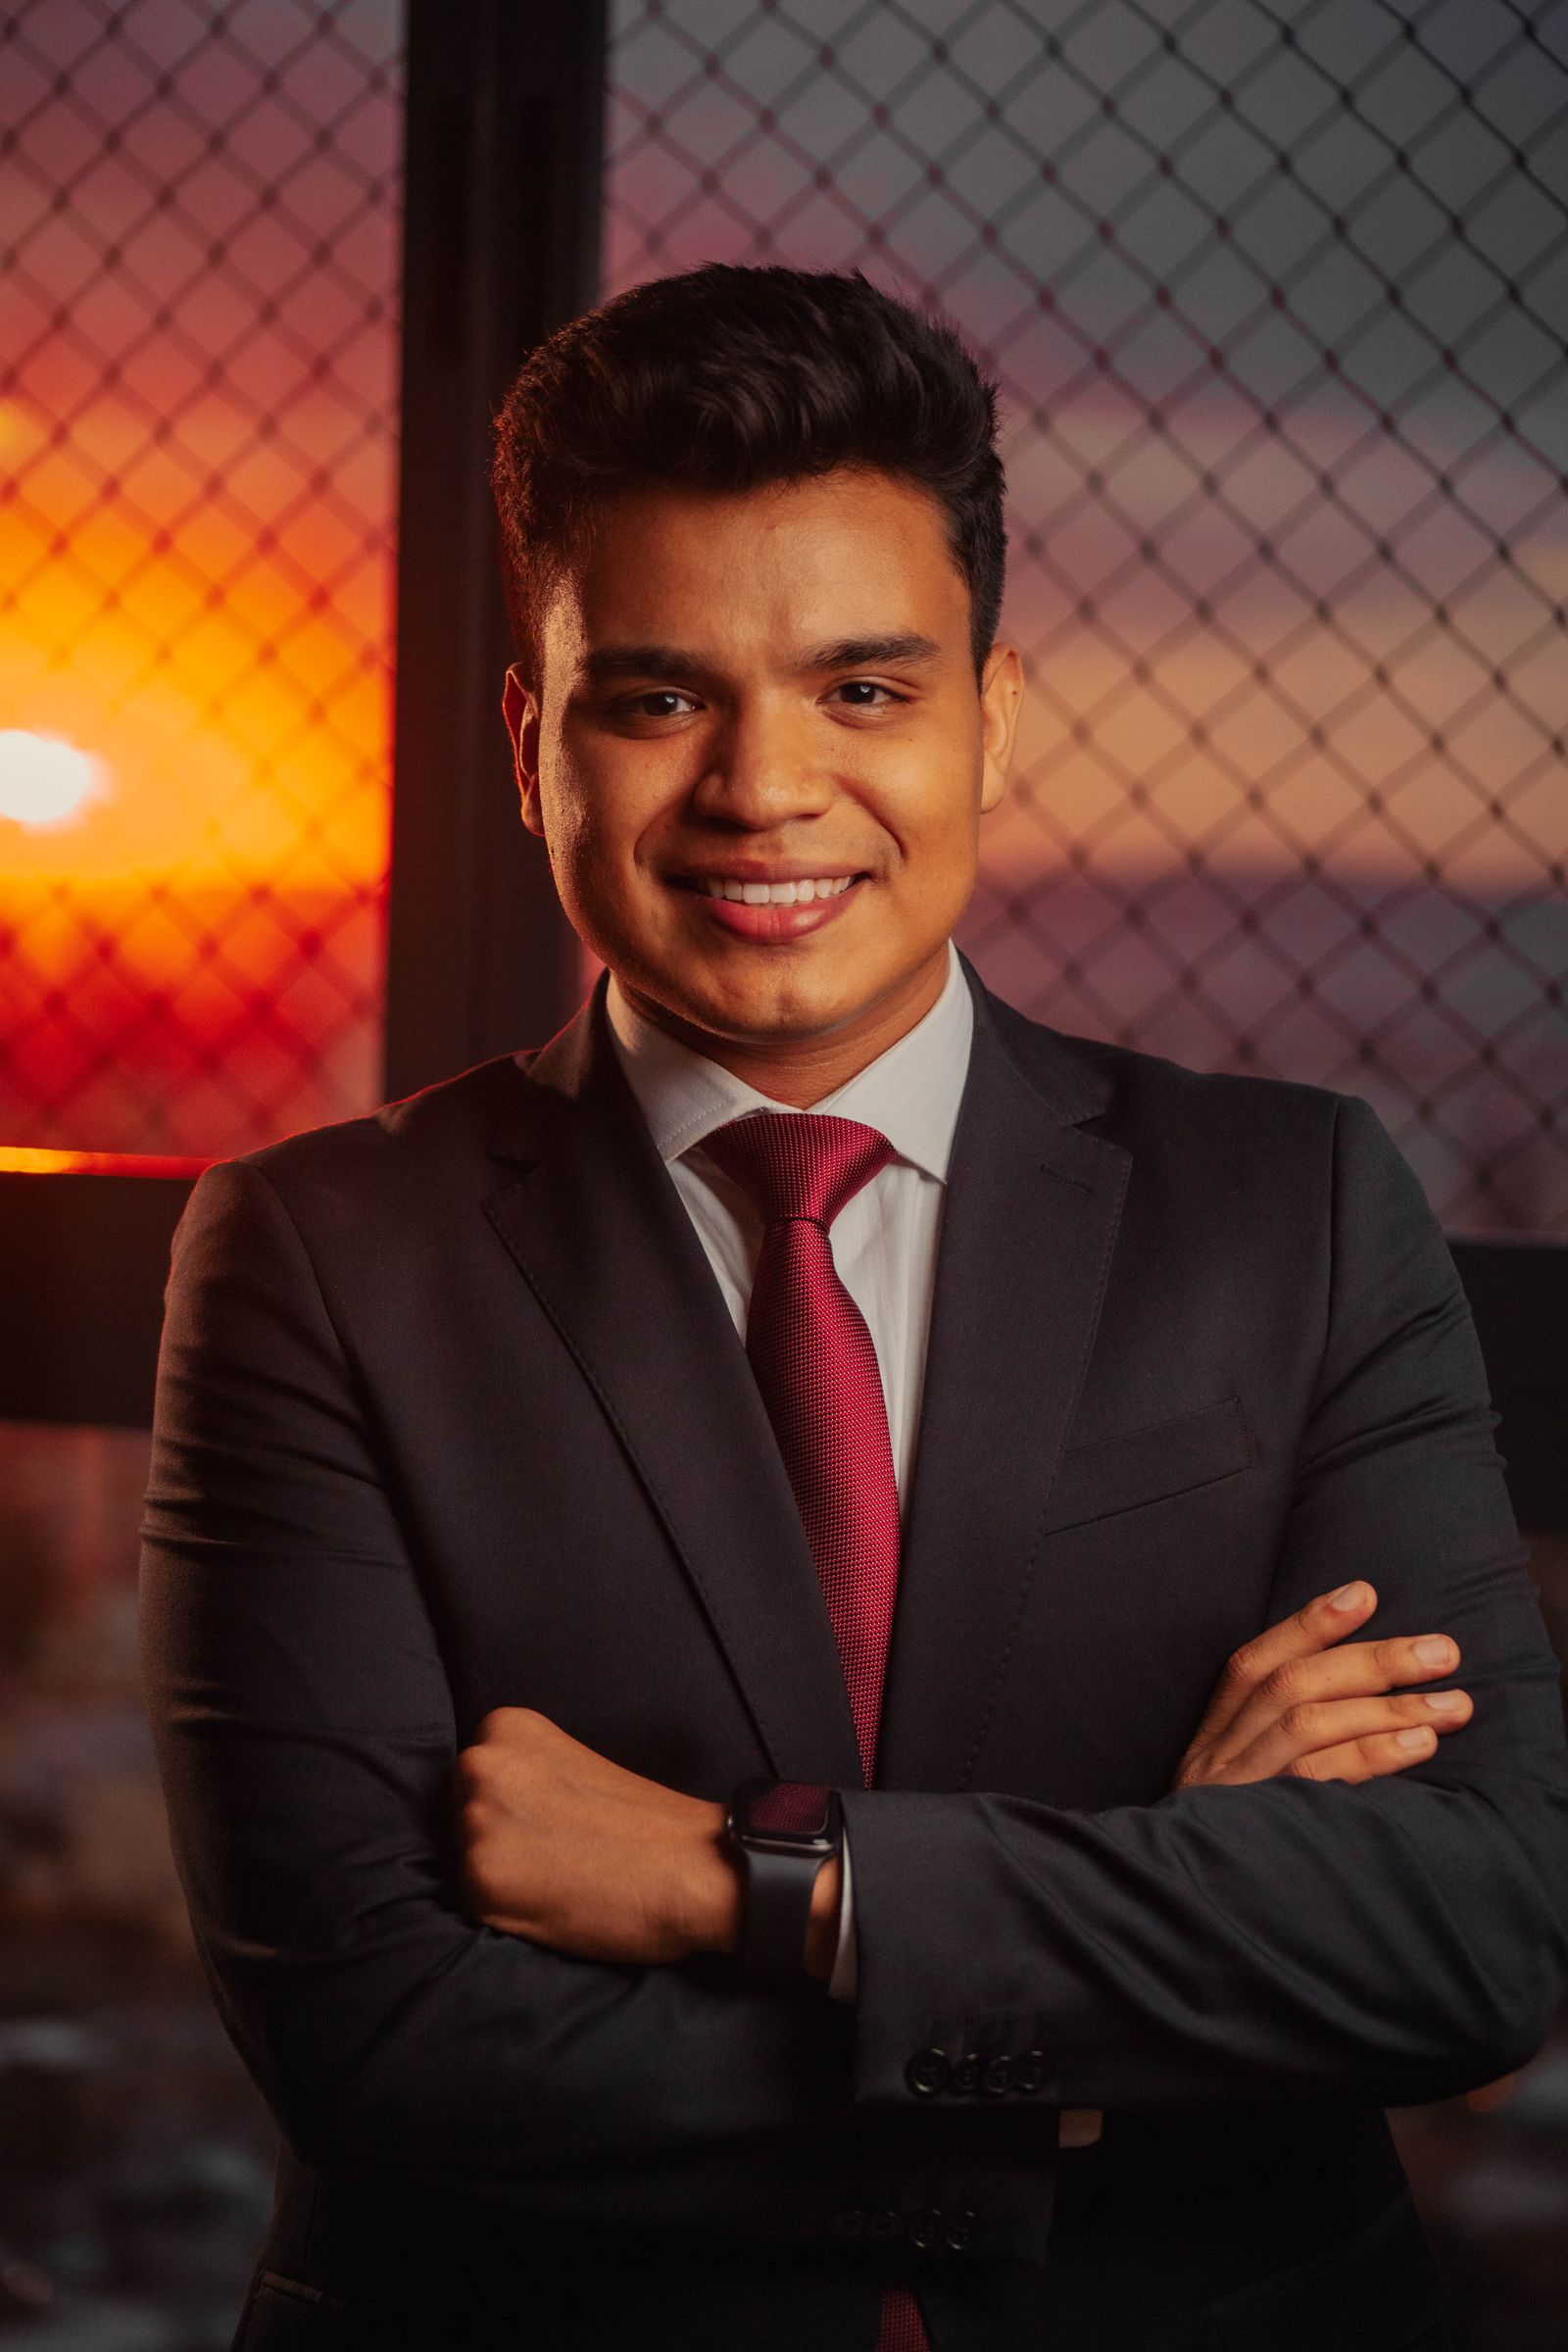
  • Daniel Whitfield, Principal and branch manager

    Daniel Whitfield

    Principal and branch manager

    NMLS #XXXXXXX

    Jumbo, self-employed, portfolio structuring

  • Yasmin Haddad, Senior loan officer, purchase

    Yasmin Haddad

    Senior loan officer, purchase

    NMLS #XXXXXXX

    First-time buyers, FHA, PHFA assistance layering

  • Rohan Venkatesan, Loan officer, refinance and home equity

    Rohan Venkatesan

    Loan officer, refinance and home equity

    NMLS #XXXXXXX

    Rate and term, cash-out, HELOC and second liens

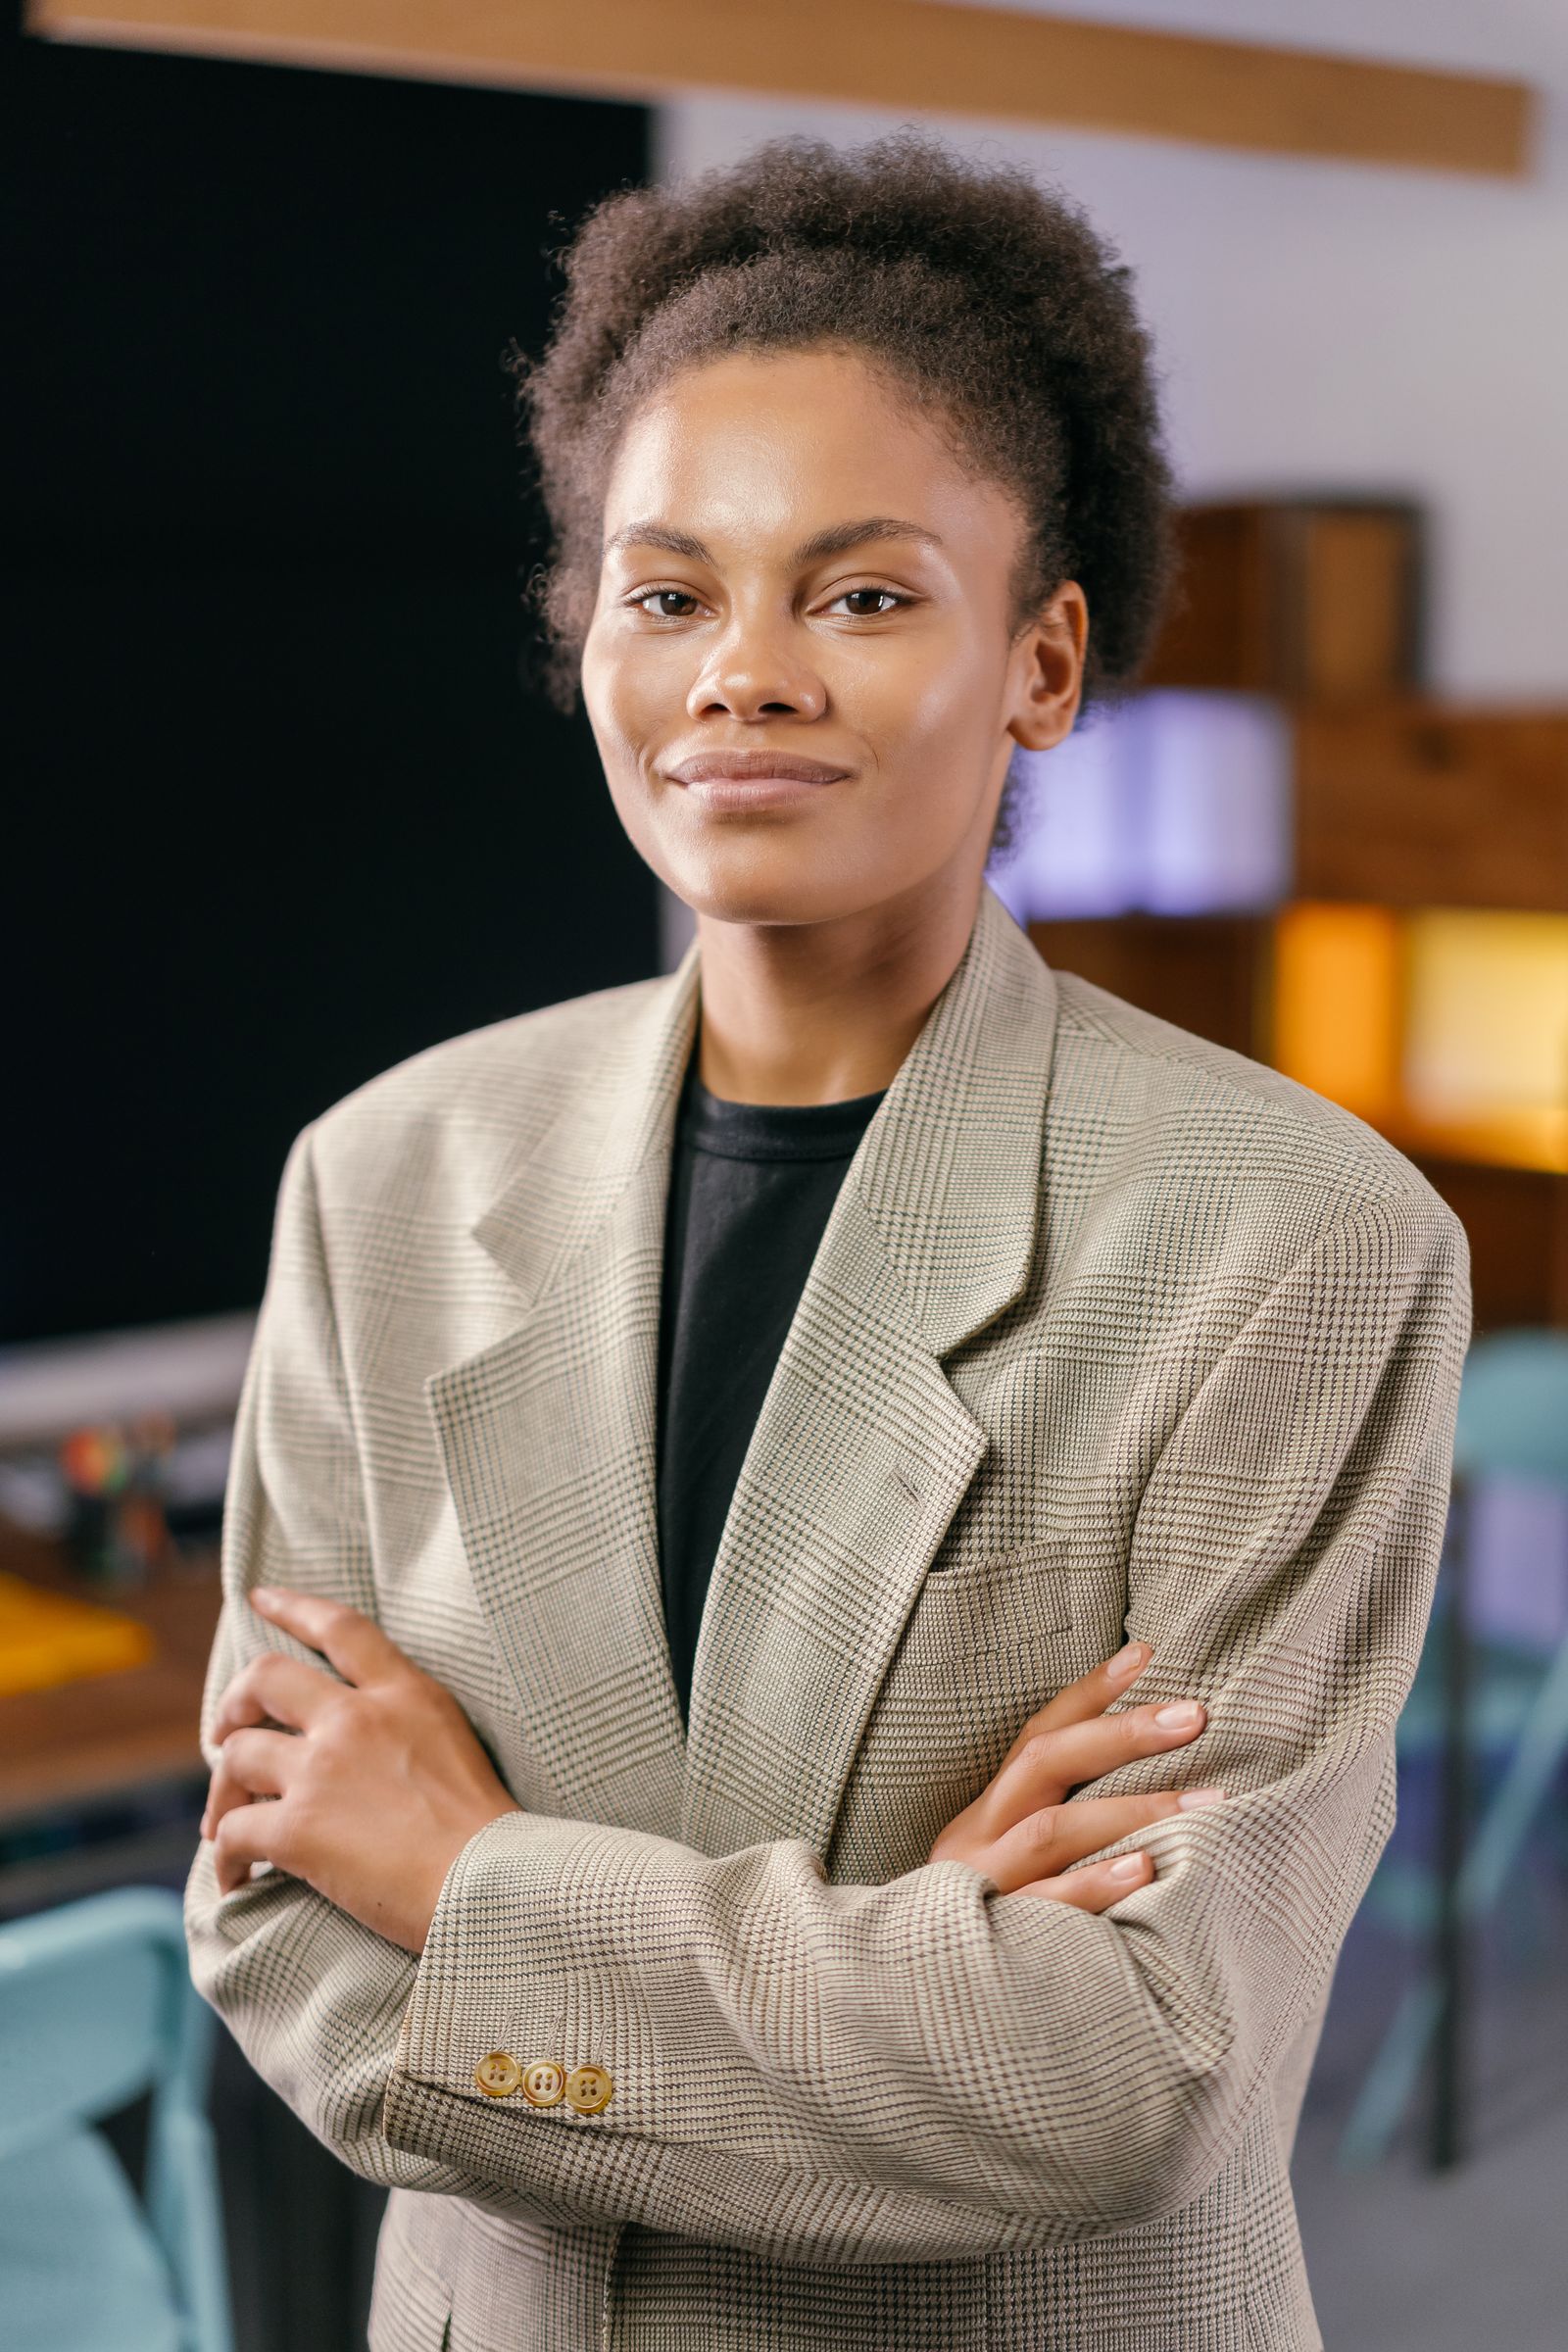
  • Amara Okonkwo, Investor lending lead

    Amara Okonkwo

    Investor lending lead

    NMLS #XXXXXXX

    DSCR, fix and flip, bridge, blanket portfolios

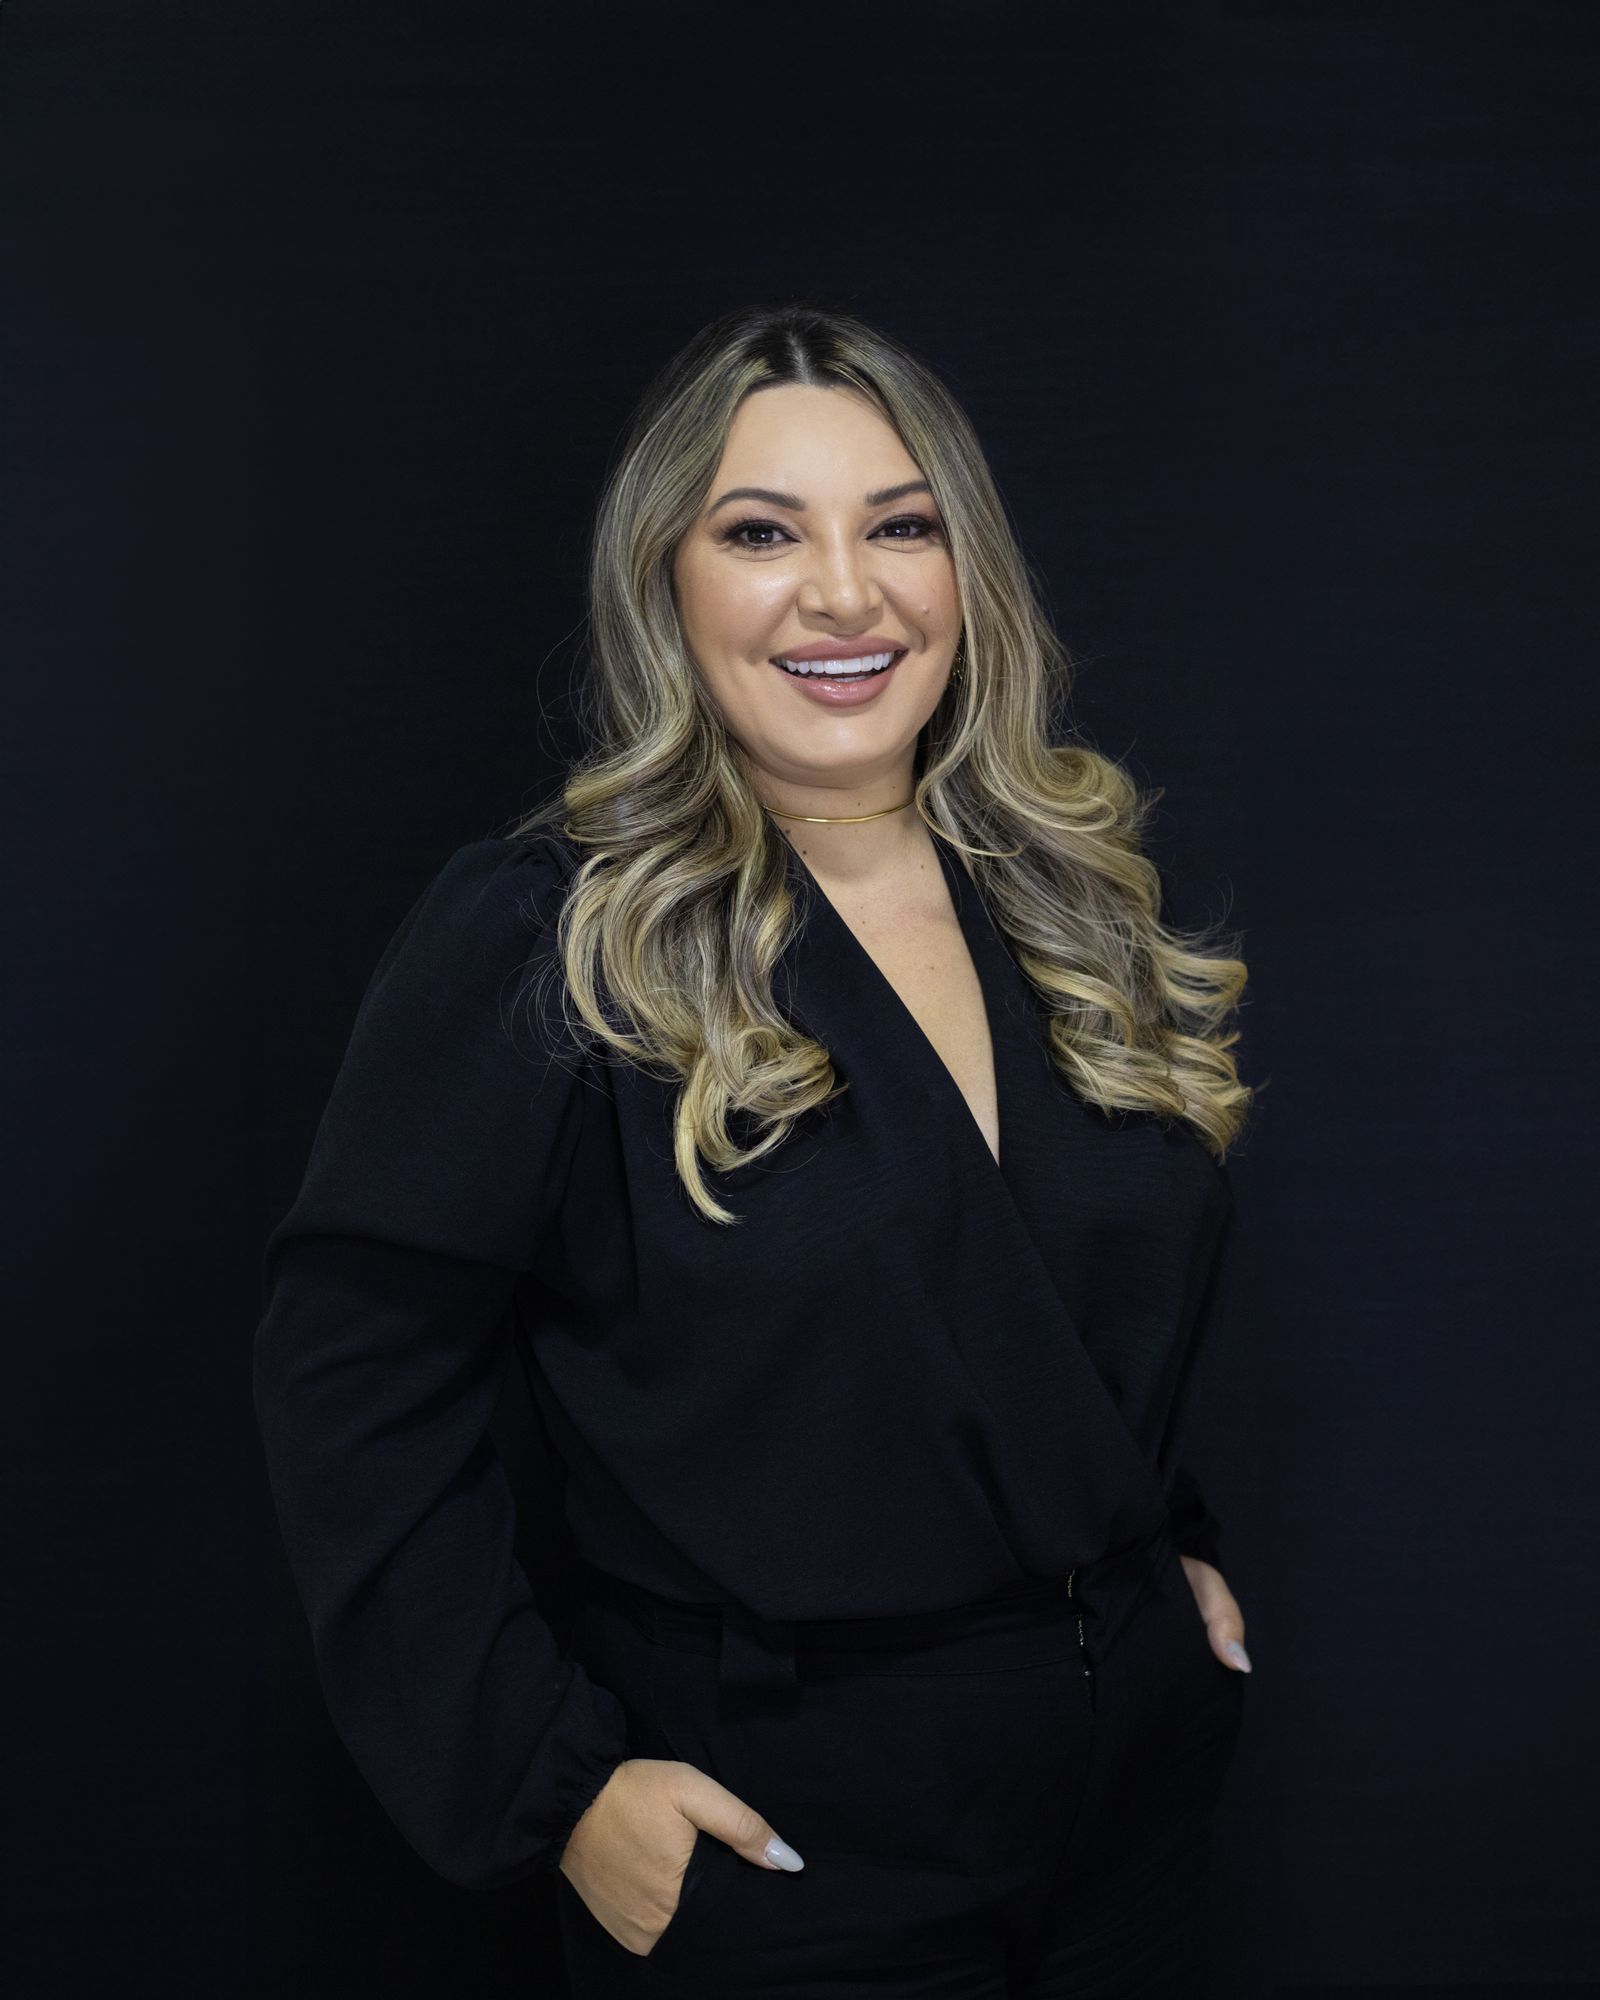
  • Hannah Brenner, Jumbo and self-employed specialist

    Hannah Brenner

    Jumbo and self-employed specialist

    NMLS #XXXXXXX

    Bank statement income, asset depletion, restricted stock

  • Andre Sutton, Processing and closing manager

    Andre Sutton

    Processing and closing manager

    Not a licensed originator

    Conditions, title coordination, settlement

Read the full bios

What a point costs, and the month it pays you back

Five pricing options on the same $400,000 loan. The break-even is simply the cost divided by the genuine monthly saving, and on this grid it lands at about five years either way.

Base case: $400,000 loan, 30 year fixed, par rate 6.125%, principal and interest $2,430.

  • Lender creditLowest cash to close

    6.375%

    $2,495 / month

    Cost at closing
    $4,000 credit
    Versus par each month
    $65 more
    Break-even
    Credit now, $65 more each month

    $4,000 received, $3,900 paid back by month 60

  • Par pricing

    6.125%

    $2,430 / month

    Cost at closing
    None
    Versus par each month
    Baseline
    Break-even
    No cost, no buydown

    Baseline for comparison

  • Half point

    6.000%

    $2,398 / month

    Cost at closing
    $2,000
    Versus par each month
    $32 less
    Break-even
    62 months

    $1,920 saved against $2,000 paid

  • One pointMost chosen

    5.875%

    $2,366 / month

    Cost at closing
    $4,000
    Versus par each month
    $64 less
    Break-even
    62 months

    $3,840 saved against $4,000 paid

  • Two points

    5.625%

    $2,302 / month

    Cost at closing
    $8,000
    Versus par each month
    $128 less
    Break-even
    63 months

    $7,680 saved against $8,000 paid

Sample pricing, expires with the rate sheet. Buydown grids are republished each business morning and this one is an illustration for a demonstration site. It is not a quote, not a lock and not an offer to lend. Your own grid depends on credit score, loan-to-value, occupancy and lock period.

See the full rate sheet

The part we control

The Keystone flat-fee promise

Rates move every morning and third-party fees belong to other people. Our own fee schedule does not move, and it is the same on a $150,000 loan as on a $1,500,000 one.

See every closing cost
  • Loan Estimate within three business days of application
  • Closing Disclosure reconciled against it line by line
  • Wire instructions confirmed by phone callback, every time
Origination and underwritingNot a percentage. The same on a $150,000 loan and a $1,500,000 loan.
$1,095 flat
Application feeWe do not charge to look at your file.
$0
Rate lock extension caused by usIf the delay is ours, we buy the extension.
$0
Float-down when the market improvesMarket minus 0.125%, requested 10 days before settlement.
One free
Origination on a repeat refinanceIf Keystone originated your current loan.
Waived

Sample fee schedule for demonstration. Third-party and government charges are set by others and are itemized separately on your Loan Estimate.

Licensed, approved and audited

  • Equal Housing Opportunity lender
  • In-house underwriting since 2009
  • Licensed in PA, NJ, DE and MD
  • Fannie Mae and Freddie Mac seller-servicer
  • FHA, VA and USDA approved
  • 4.9 from 1,284 closed-file surveys

Sample credentials for a demonstration site. NMLS identifiers are placeholders pending the client's licensing details.

Cookie preferences

Choose which cookies you allow. You can change this at any time from the link in the footer.