





Purchase
USDA guaranteed loans
Most buyers assume they do not qualify. Check the map before you assume.
What a USDA guaranteed loan actually is
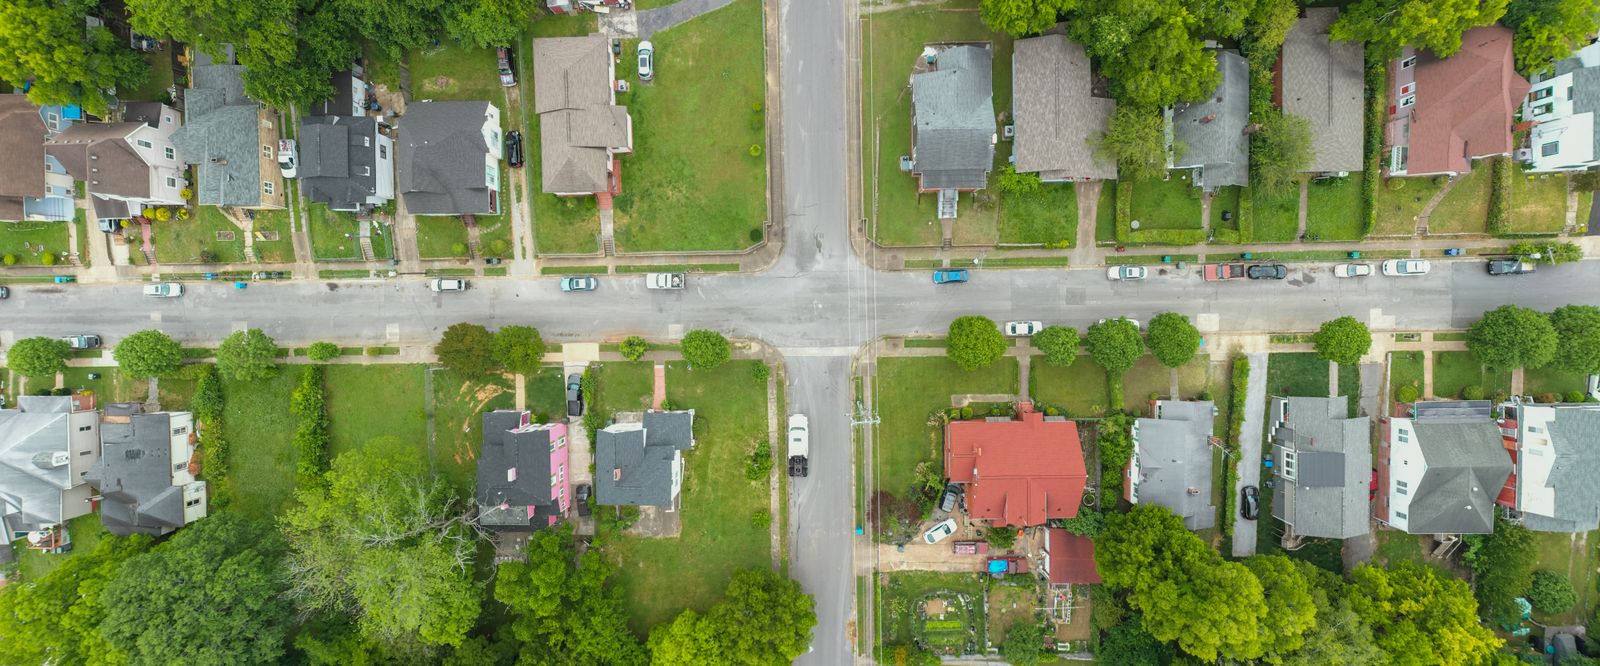
The USDA Single Family Housing Guaranteed Loan is a zero-down program for moderate-income households in eligible areas. The word rural is misleading. Sizeable parts of upper Bucks County, northern Chester County, western Berks and the Lehigh Valley fringe are eligible, and a fair number of our USDA borrowers commute into Philadelphia.
Two tests decide it: the property must sit in an eligible census tract, and total household income must not exceed 115% of the area median for the county, counting every adult in the home whether or not they are on the loan. Both are checkable in about five minutes, and we do it before you fall in love with a listing.
Best suited to
- Buyers looking at upper Bucks, northern Chester, Berks or the Lehigh Valley
- Households under the county income cap with little cash to close
- Borrowers who would otherwise take FHA and carry permanent MIP
- First purchases where a seller is willing to contribute to costs
What comes with the loan
- Property eligibility check against the current USDA map before you write an offer
- Household income worksheet covering every adult occupant, not just the borrowers
- GUS submission and findings the same business day
- Guidance on the difference between the guaranteed and the direct 502 program
- Coordination with the USDA state office on conditional commitment timing
- Seller concession structuring, since USDA allows up to 6% toward closing costs
How a file moves
- 01
Two eligibility checks
Property map and household income. Either one failing ends the conversation, so we do both in the first call.
- 02
Pre-approval and GUS
Full documents run through the Guaranteed Underwriting System. A GUS Accept is what makes the rest of the file straightforward.
- 03
Appraisal
A standard appraisal with USDA's own condition requirements. Private well and on-site septic systems need testing and are common in eligible tracts.
- 04
Conditional commitment
After our underwriting clears, the file goes to the USDA state office for its commitment. Budget five to ten business days for that step; it is outside our control and we say so.
- 05
Closing
Total time from contract to settlement on our USDA files runs 35 to 45 calendar days (sample figure), longer than conventional because of the agency step.
Why borrowers choose it
True zero down
No down payment, and the 1.00% guarantee fee can be financed into the loan amount.
Cheaper than FHA monthly
The 0.35% annual fee is well below FHA's 0.55%, which on a $300,000 loan is about $50 a month.
Generous seller concessions
Up to 6% of the price may come from the seller toward closing costs and prepaids.
Finance above appraised value
The guarantee fee may be financed even if it pushes the loan slightly above the appraised value.
What to watch out for
- Income counts every adult in the household, including a parent living with you who is not on the loan.
- The agency commitment step adds a week or more to the timeline; do not agree to a 30-day settlement.
- Eligible-area maps change. An address eligible two years ago may not be eligible now.
USDA guaranteed questions we get asked
Still unclear? Call (215) 555-0145 and ask for the originator covering your county.
All questionsSend it to us and we will check it against the current USDA eligibility map while you are on the phone. Large parts of upper Bucks, northern Chester, western Berks and the Lehigh Valley fringe qualify. Philadelphia County itself does not.
Every adult who will live in the home, whether or not they are a borrower and whether or not their income is used to qualify. That includes an adult child working part time and a parent receiving social security. It is the most common reason a USDA file fails late.
The guaranteed program is made by a lender such as Keystone with a USDA guarantee behind it. The direct 502 program is lent by USDA itself to very low and low income households, with payment subsidy. We originate the guaranteed product and will point you to your state office for direct.
Yes, and it is common in eligible areas. USDA requires water potability testing and a septic inspection where state or local rules call for one. We order both early because results take time.
Programs worth comparing

FHA
3.5% down from a 580 score, 10% down from 500
Conventional
Conforming loans to $832,750 with cancellable PMI
First-time buyer
PHFA pairing, grant stacking and the 3% down route
Find out if USDA guaranteed fits
Fifteen minutes, a soft credit pull, and a straight answer about which program actually suits your file.
No application fee. Soft credit pull at pre-qualification. Flat $1,095 origination at closing.