






Since 2009
A lender that kept its underwriting
Keystone was built around one decision: the person who says yes should sit in the same building as the person who asked. Everything else follows from that.
Why this exists
In 2009 there were two kinds of mortgage company in Philadelphia: banks that had stopped lending, and brokers who sent every file to an out-of-state desk and relayed the answers back a day late. Dara Whitfield had spent eleven years as the person on that desk and knew exactly how much was lost in translation.
So Keystone was built the other way round. Underwriting came first and origination was added to it, rather than the reverse. That is an unusual structure for a company our size, it costs more to run, and it is the only reason our median from complete file to clear-to-close is 12 business days rather than 30.
Seventeen years later we have six offices, four state licenses and about sixty loans a month. The part that has not changed is the fourteenth floor at 1701 Market Street, where every file is still read by a person whose name appears on the pre-approval letter.
Keystone in numbers
- 1,284Closed-file client surveys since 2009
- 12 daysMedian complete file to clear-to-close
- 4 statesPA, NJ, DE and MD
- $1,095Flat origination fee, any loan size
Sample figures for this demonstration site.
Four rules we actually keep
Underwrite it here
Files are underwritten on the fourteenth floor at 17th and Market, not in a processing center three states away. When a condition looks wrong, someone walks over and asks.
Publish the fee
$1,095 flat, the same on a $150,000 loan and a $1,500,000 one. A percentage-based origination charges three times as much for identical work.
Show the arithmetic
Break-even months, the binding ratio, the full amortization schedule. If the numbers say do not do this, we would rather you heard it from us.
Batch the conditions
Issued once, not weekly. Most of what clients remember about a mortgage is how many times they were asked for something they had already sent.
Seventeen years, five moments
- 2009
Two people and a rented office
Dara Whitfield left eleven years of bank underwriting to open Keystone in the middle of the worst mortgage market in living memory. The first year closed 31 loans.
- 2013
Purchase desk
Tomás Delgado joined to run first purchases. South Philadelphia, Kensington and Point Breeze were still affordable, and PHFA assistance was going unclaimed.
- 2017
Investor desk
Amara Okonkwo opened DSCR and bridge lending after her own portfolio hit the agency ten-property limit and no local lender could help.
- 2021
Four states
New Jersey, Delaware and Maryland licenses added, and the Cherry Hill and Wilmington offices opened to serve them properly rather than remotely.
- 2026
Six offices, one underwriting floor
Six locations take applications. All of them underwrite in Center City, which is the part we refuse to distribute.
Six people you can actually reach
NMLS identifiers shown are placeholders pending the client's licensing details.
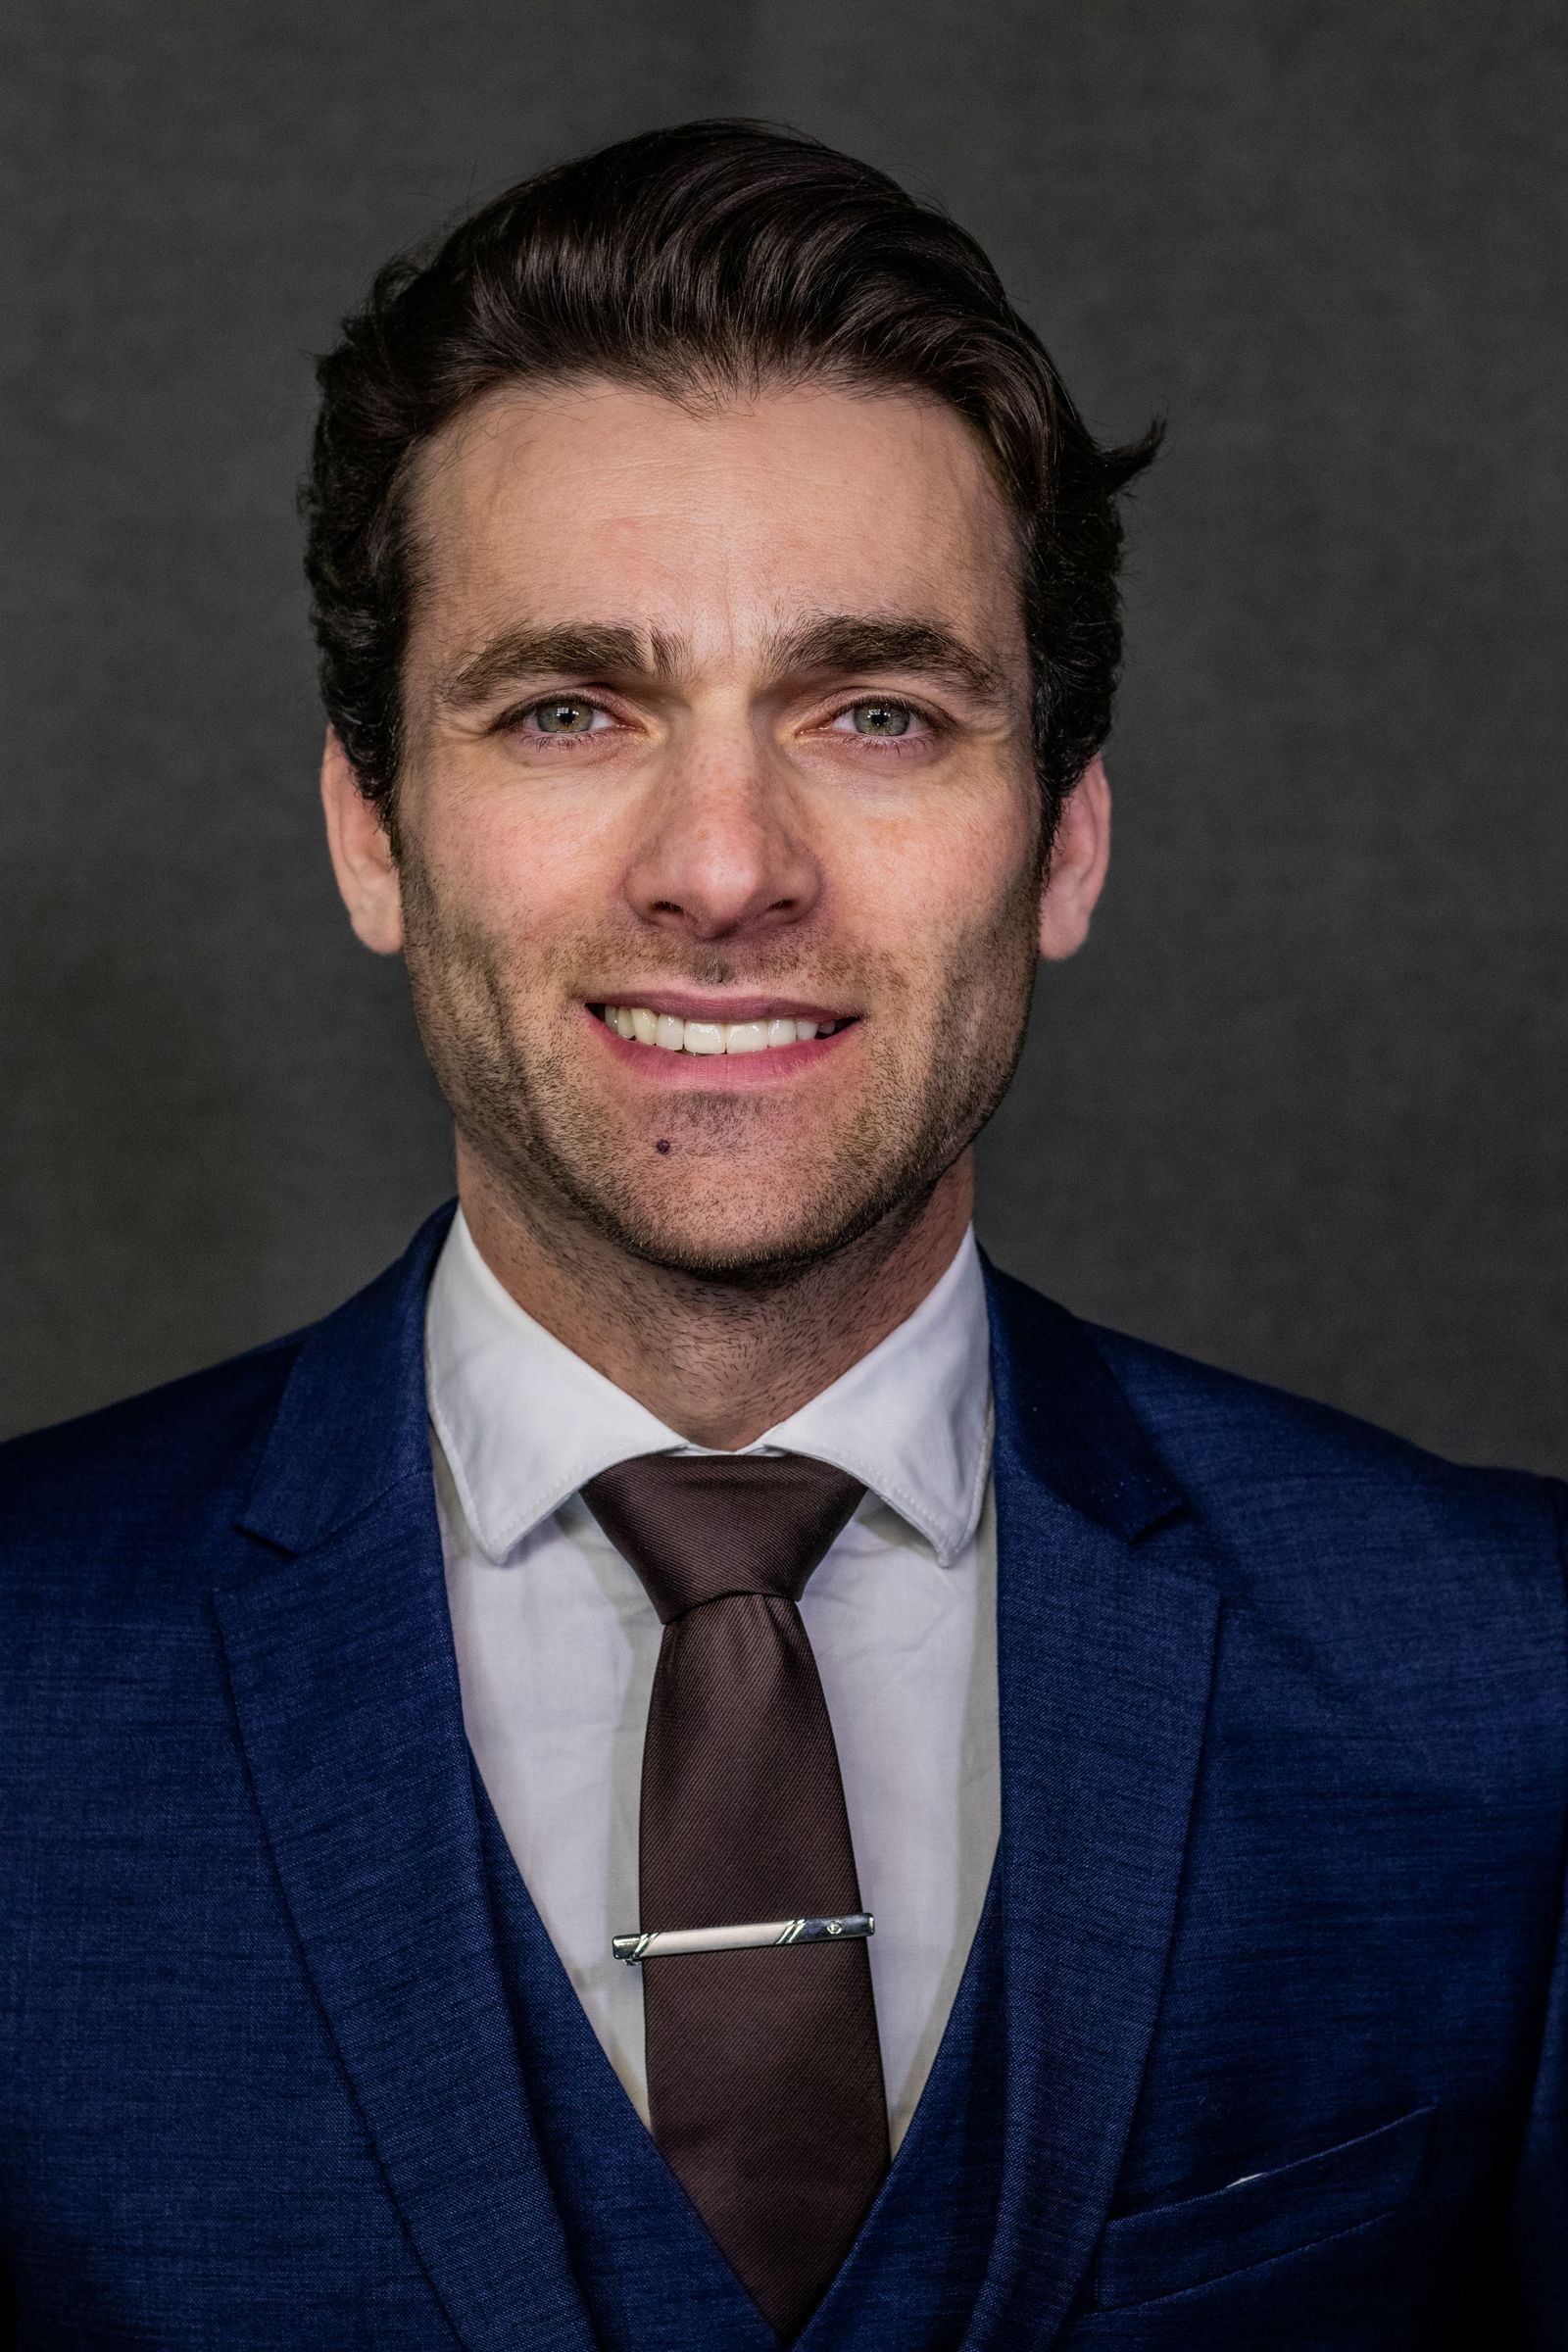
Daniel Whitfield
Principal and branch manager
NMLS #XXXXXXX
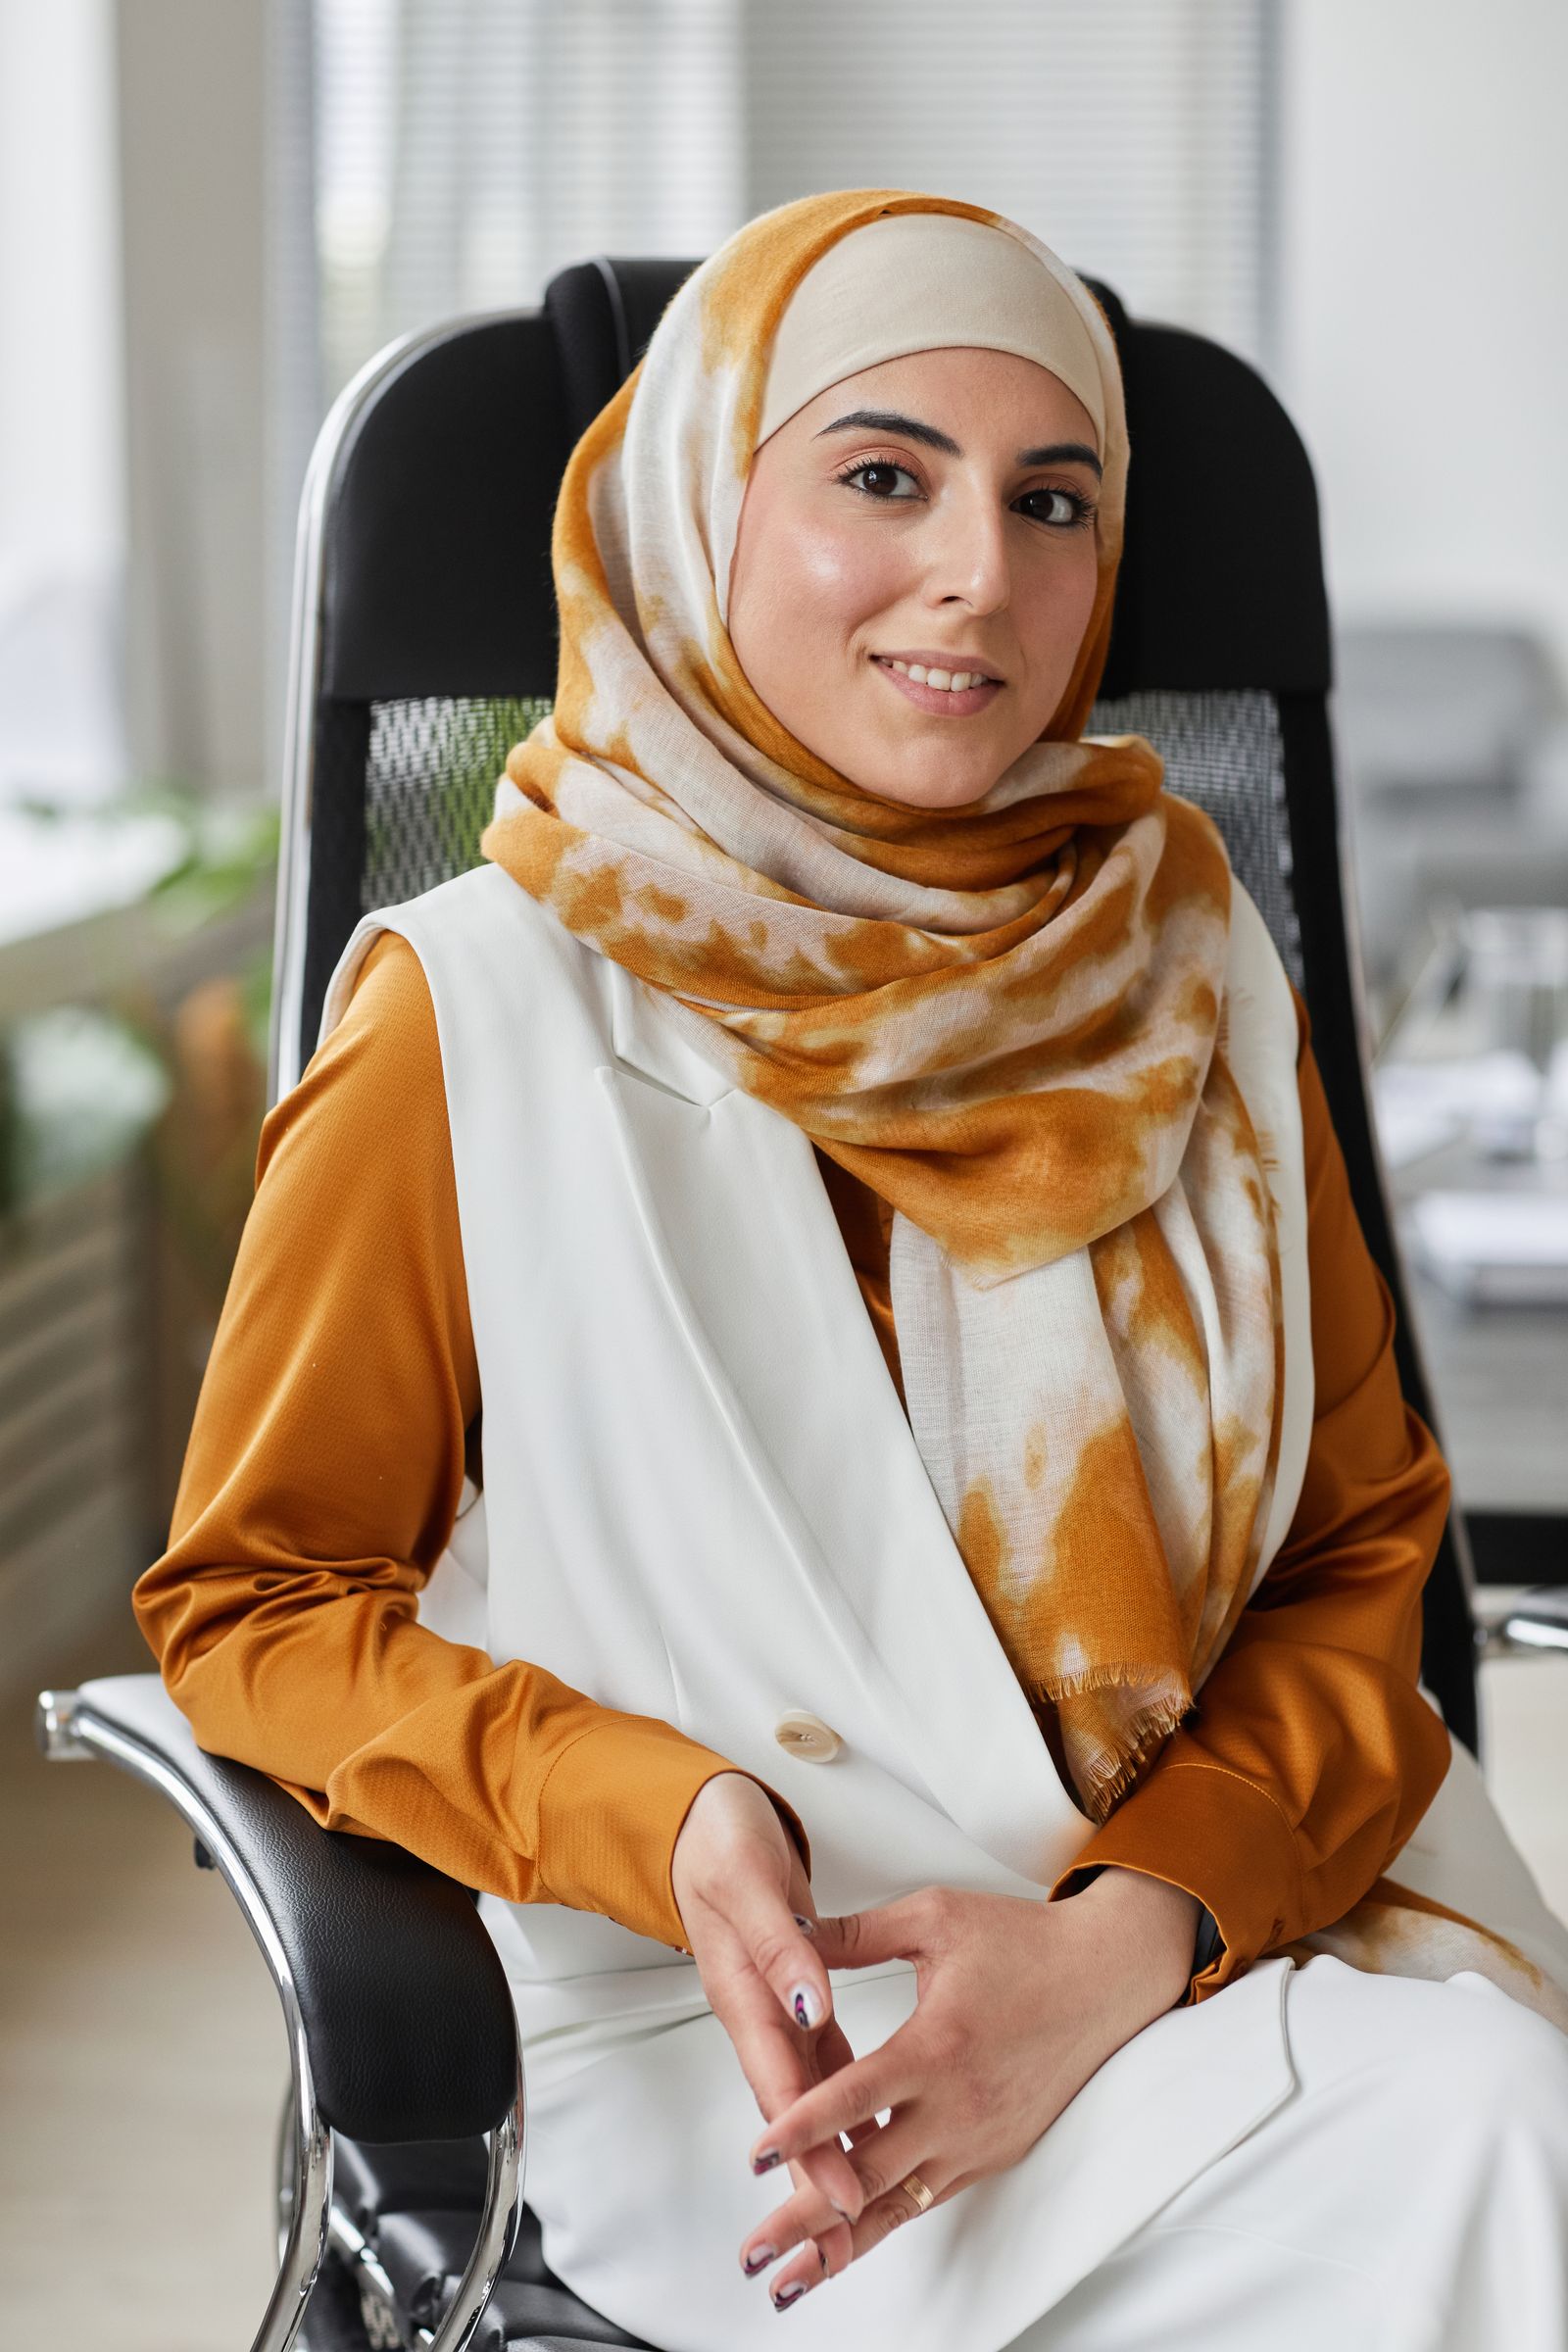
Yasmin Haddad
Senior loan officer, purchase
NMLS #XXXXXXX
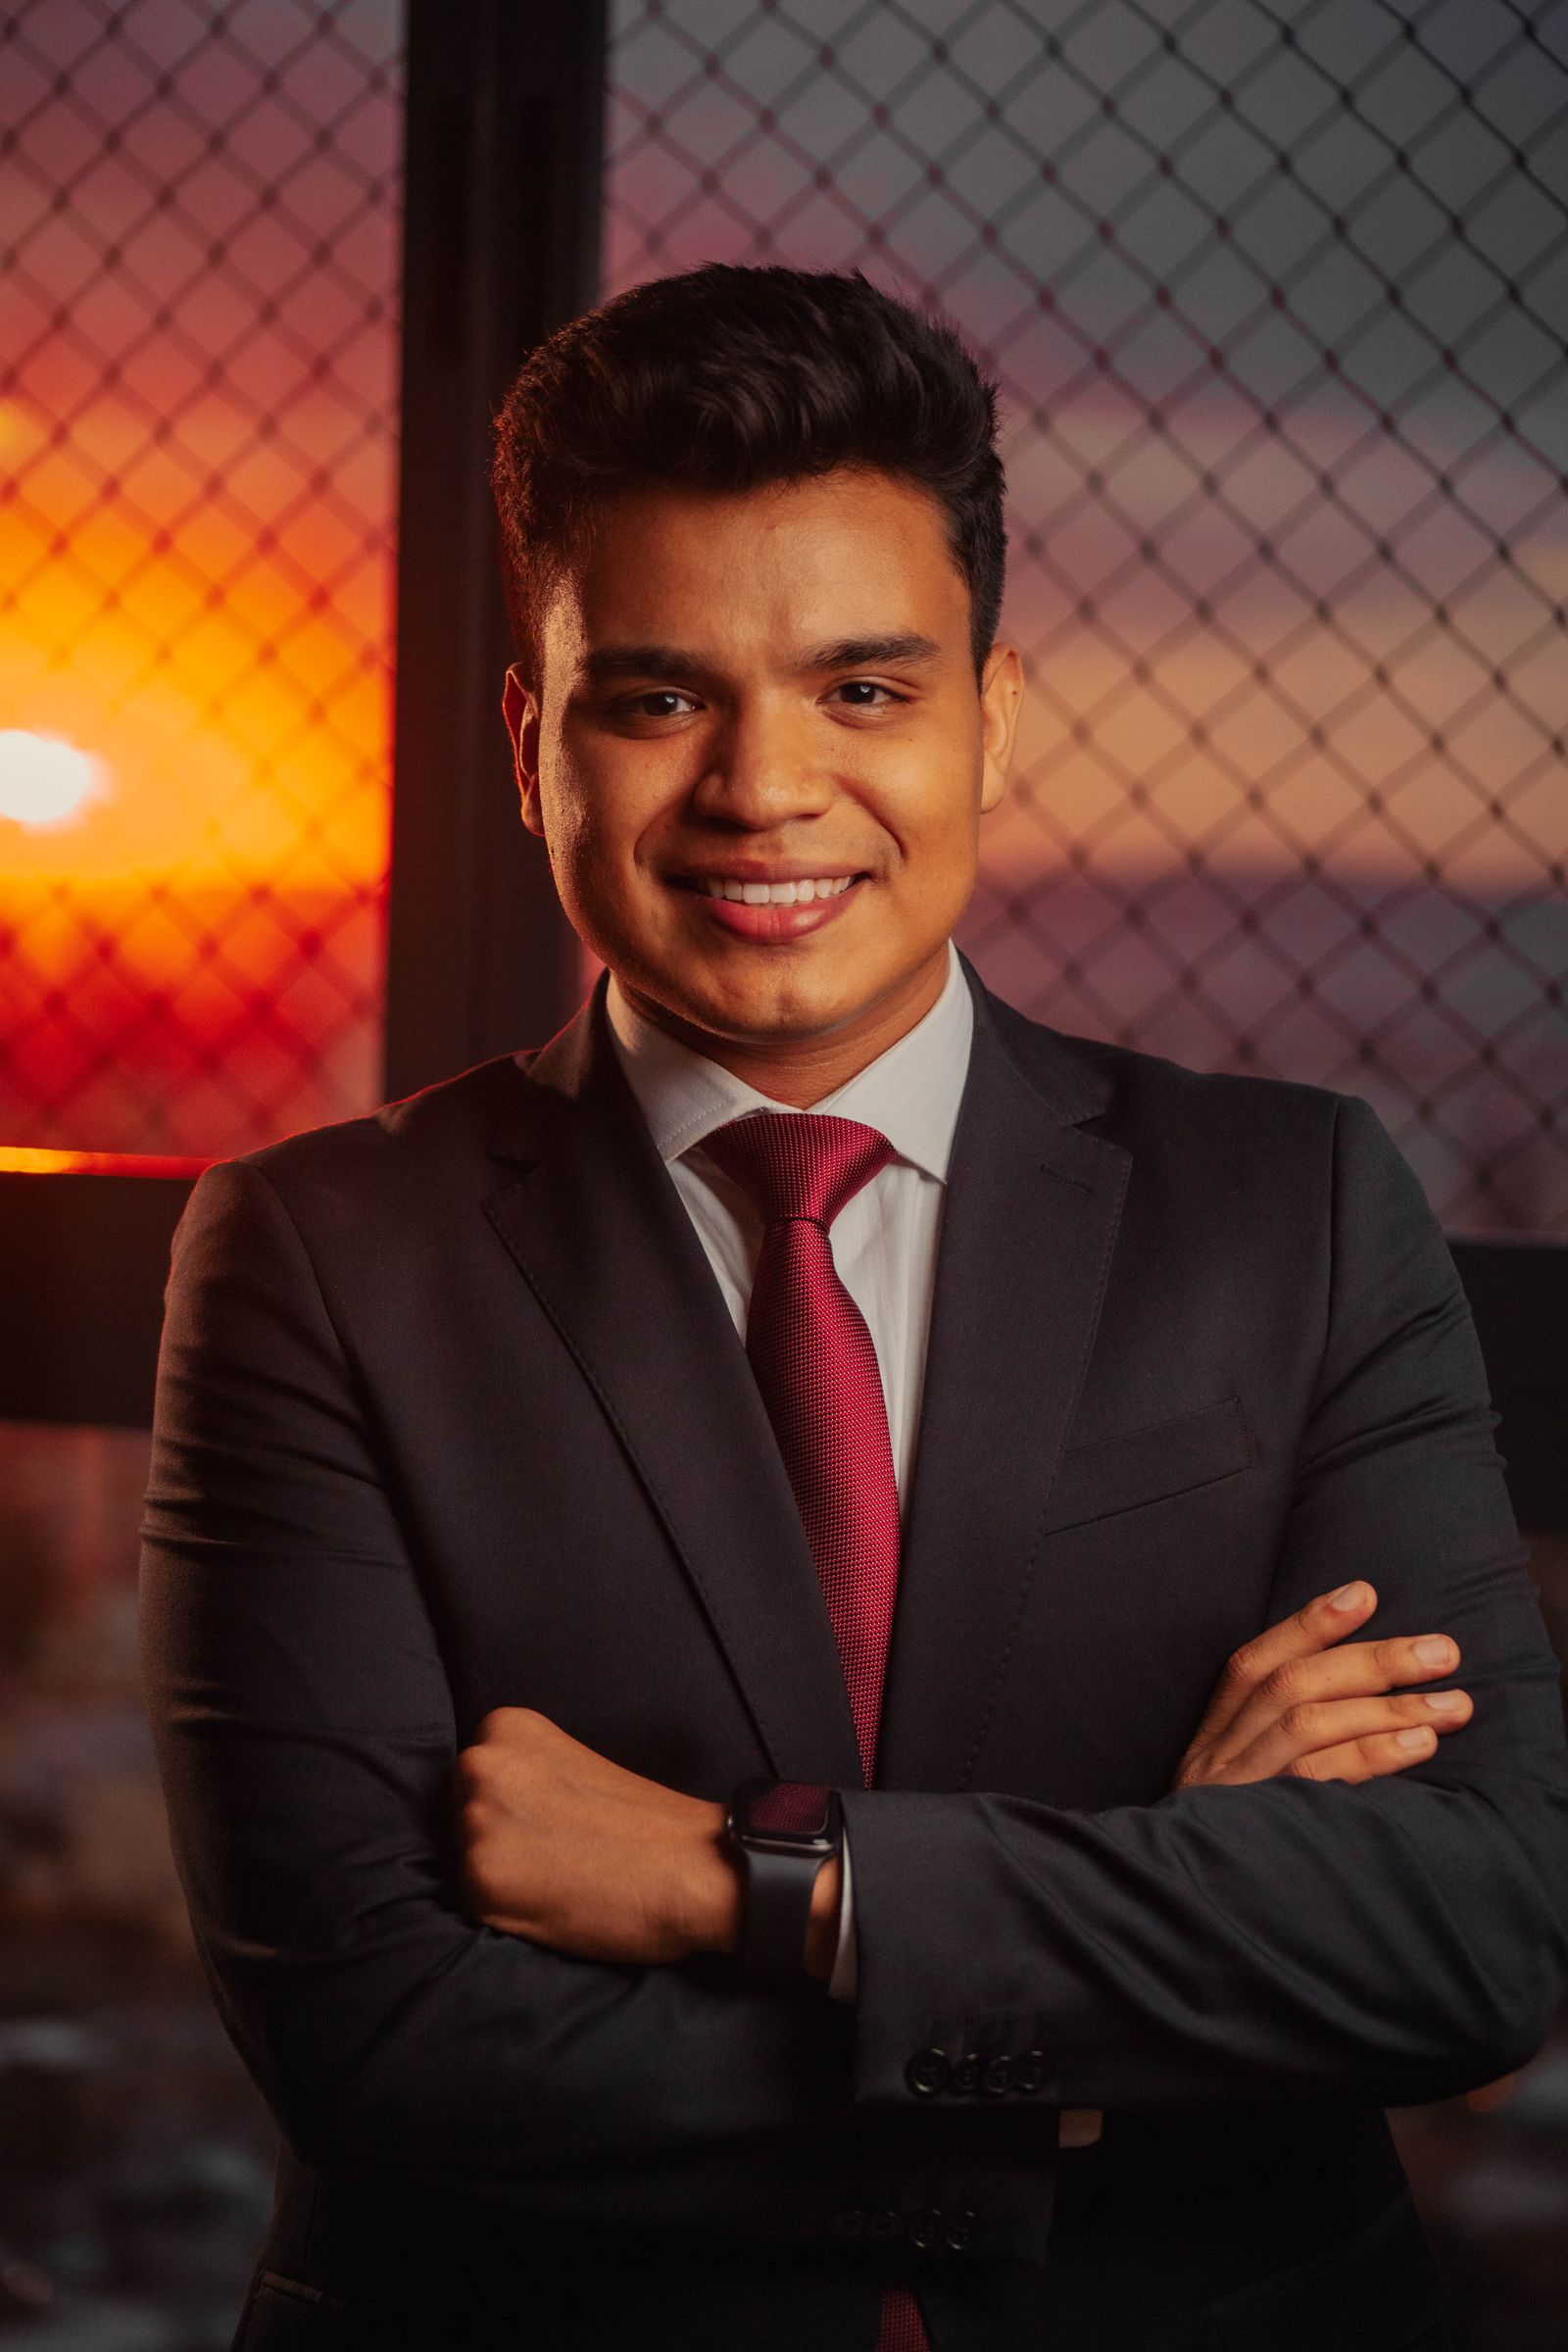
Rohan Venkatesan
Loan officer, refinance and home equity
NMLS #XXXXXXX
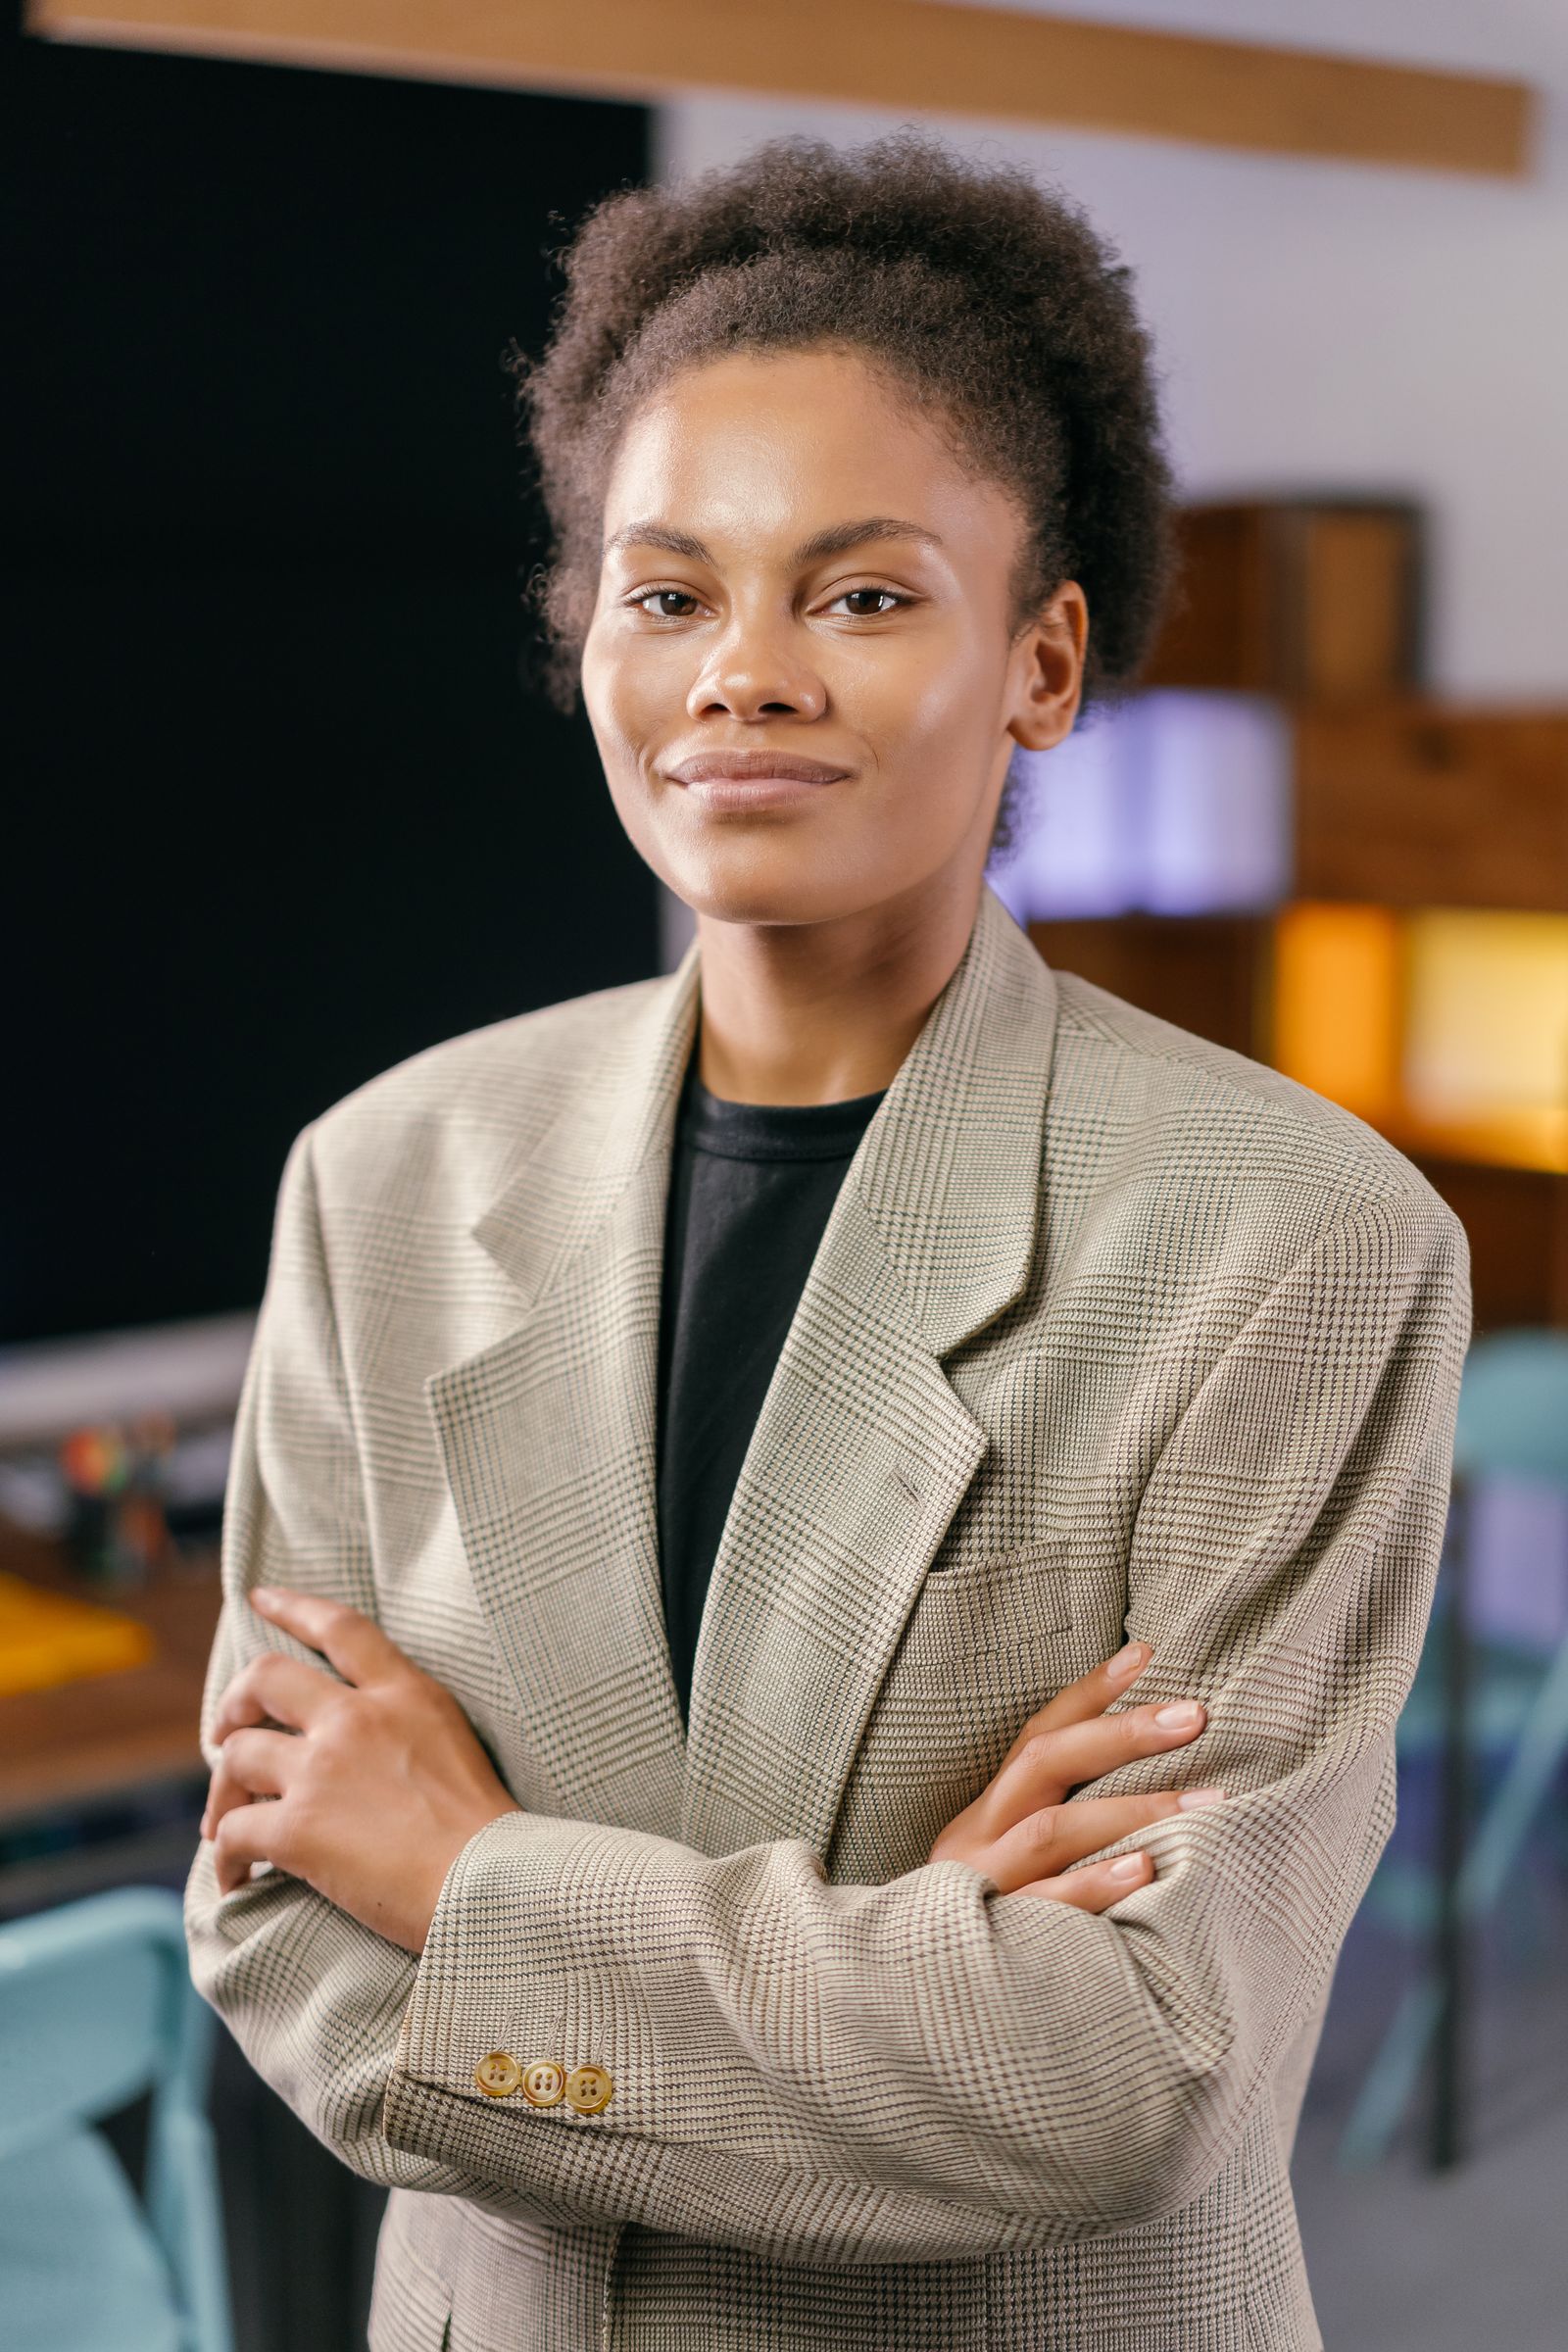
Amara Okonkwo
Investor lending lead
NMLS #XXXXXXX
Licensing and disclosures
Keystone Capital Mortgage, NMLS #XXXXXXX. Licensed by the Pennsylvania Department of Banking and Securities, the New Jersey Department of Banking and Insurance, the Delaware Office of the State Bank Commissioner and the Maryland Office of the Commissioner of Financial Regulation. The NMLS number shown is an obvious placeholder pending the client's real licensing details.
Read the full disclosures
Find out what you qualify for
A fifteen minute call, a soft credit pull and a straight answer about the program and price range that actually fit.
No application fee. Soft credit pull at pre-qualification. Flat $1,095 origination at closing.
Licensed, approved and audited
- Equal Housing Opportunity lender
- In-house underwriting since 2009
- Licensed in PA, NJ, DE and MD
- Fannie Mae and Freddie Mac seller-servicer
- FHA, VA and USDA approved
- 4.9 from 1,284 closed-file surveys
Sample credentials for a demonstration site. NMLS identifiers are placeholders pending the client's licensing details.